
Commonwealth Equity Services, LLC, doing business as Commonwealth Financial Network, is a broker-dealer and registered investment adviser identified on regulatory filings by CRD# 8032 and CIK 0000312272. The firm reports regulatory assets under management of roughly $212.66 billion and about 4,200 employees as of its most recent filings. The headline fact investors and advisors search for is the enforcement matter: the SEC pursued a civil action alleging Commonwealth failed to disclose revenue-sharing conflicts of interest, and that dispute reached the First Circuit Court of Appeals, which issued an opinion in 2025.
None of this requires taking anyone’s word for it. Every fact below traces to a primary source you can pull up yourself.
- Legal identity: Commonwealth Equity Services, LLC (d/b/a Commonwealth Financial Network)
- Identifiers: CRD# 8032, CIK 0000312272
- Reported scale: approximately $212.66 billion AUM, roughly 4,200 employees
- Regulatory headline: SEC enforcement action over undisclosed revenue-sharing arrangements, with a First Circuit appellate decision issued in 2025
- Where to verify: SEC EDGAR, Adviserinfo, and FINRA BrokerCheck
Key Takeaways
Commonwealth Equity Services, LLC (CRD# 8032, CIK 0000312272) is a verified broker-dealer and RIA whose 2025 First Circuit appeal centered on undisclosed revenue-sharing conflicts from 2014 to 2018.
| Point | Details |
|---|---|
| Confirm identity first | Use CRD# 8032 on BrokerCheck and CIK 0000312272 on EDGAR before trusting any secondhand summary. |
| Know the business model | Commonwealth supports independent advisors; most clients’ custody sits with a separate clearing firm, not Commonwealth directly. |
| Understand the enforcement matter | The SEC alleged undisclosed revenue-sharing with National Financial Services covering 2014 to 2018 conduct. |
| Read Form CRS first | It’s shorter than the ADV brochure and built specifically to surface conflicts and fees for comparison. |
| Escalate methodically | Start with EDGAR and BrokerCheck verification, then move to a FINRA complaint or private counsel if losses are involved. |
Table of Contents
- What Is Commonwealth Equity Services LLC’s Official Company Profile?
- How Do You Find Commonwealth’s Regulatory Filings?
- What Services Does Commonwealth Financial Network Actually Provide?
- What Did the SEC Allege Against Commonwealth Equity Services?
- How Do You Verify Commonwealth’s Records Yourself?
- What This Enforcement Case Signals for Disclosure Practice
- Ready to Look Into Your Own Situation?
- A Verification-First Read on the Commonwealth Case
- Sources
- FAQ
What Is Commonwealth Equity Services LLC’s Official Company Profile?
Commonwealth Equity Services, LLC operates under the trade name Commonwealth Financial Network, and both names point to the same registered entity on file with the SEC. That distinction matters for anyone searching public records, because filings, court documents, and press releases sometimes use one name and sometimes the other.
The firm’s principal place of business, according to its X-17A-5 broker-dealer filings, is 275 Wyman Street, Suite 400, Waltham, Massachusetts 02451. Its fiscal year ends December 31, and its outside auditor is listed as RSM US LLP. Commonwealth has operated for decades as an independent broker-dealer and registered investment adviser, building its business around supporting other financial advisors rather than serving as a direct-to-consumer wealth manager.
Here are the identifiers and figures every verification search should start with:
| Field | Value |
|---|---|
| Legal name | Commonwealth Equity Services, LLC |
| Trade name (d/b/a) | Commonwealth Financial Network |
| CRD# | 8032 |
| CIK | 0000312272 |
| Headquarters | 275 Wyman Street, Suite 400, Waltham, MA 02451 |
| Reported AUM | $212.66 billion |
| Reported employees | ~4,200 |
| Fiscal year end | December 31 |
| Auditor | RSM US LLP |
A few things stand out here. The AUM figure and employee count come directly from regulatory filings indexed on EDGAR, not from marketing copy, which is precisely why they’re worth citing over a number pulled from a review site. Commonwealth’s public materials describe its own history and founding in more narrative detail, but the identifiers above are what you actually type into a search box on EDGAR, BrokerCheck, or adviserinfo.
How Do You Find Commonwealth’s Regulatory Filings?
Commonwealth Equity Services LLC’s regulatory footprint sits across four document types, and each one answers a different question. Knowing which is which saves you from digging through the wrong filing.
- Form ADV is the core registration document for investment advisers. Part 1 discloses ownership, disciplinary history, and business practices in checkbox format; Part 2 (the “brochure”) explains fees, conflicts of interest, and investment strategies in plain language. This is the single most useful document for spotting revenue-sharing arrangements before they become a problem.
- Form CRS (Customer Relationship Summary) is a short, standardized disclosure every registered firm must provide, built specifically so a retail investor can compare services, fees, and conflicts across firms side by side. Most people skip it in favor of the longer ADV brochure, which is a mistake, since CRS is designed to surface the conflict-of-interest language in under four pages.
- Form X-17A-5 is the annual audited financial report broker-dealers file with the SEC. It shows fiscal year end, auditor identity, and financial condition, the kind of information that matters if you’re trying to assess whether a firm’s back-office infrastructure is financially sound.
- EDGAR full-text and filing indexes aggregate all of the above by CIK number, letting you pull years of history in one search.
To search Commonwealth’s records directly, go to EDGAR and enter CIK 0000312272 in the company search field. That pulls every Form ADV, X-17A-5, and related filing on record. For licensing history, disciplinary events, and registered representative details, search CRD 8032 on FINRA BrokerCheck or on adviserinfo.sec.gov, which mirrors much of the same adviser-specific data.
When you open a Form ADV Part 2, focus on four fields: revenue-sharing disclosures (does the firm get paid by the products it recommends?), custody arrangements (who actually holds the client’s assets?), conflicts of interest generally, and the firm’s stated AUM as of the filing date, which you can cross-check against the EDGAR figure above.
Pro Tip: Don’t just skim the summary of material changes at the front of Form ADV. Revenue-sharing language often lives buried in a mid-document section titled something like “Additional Compensation” or “Client Referrals,” and that’s exactly the kind of clause that became central to the SEC’s case against Commonwealth.
What Services Does Commonwealth Financial Network Actually Provide?
Commonwealth is not a retail wealth manager in the way a bank’s advisory arm is. It’s an advisor-centric firm, meaning its core clients are independent financial advisors, not individual investors directly.
Commonwealth supplies the infrastructure those advisors run their practices on: trade execution, technology platforms, investment research, compliance oversight, and back-office processing. An individual investor typically never signs an agreement with Commonwealth itself. Instead, they sign an advisory agreement with an independent advisor who happens to be affiliated with Commonwealth’s broker-dealer and RIA infrastructure.
That structure has real implications for where responsibility sits:
- Client assets are usually held at a clearing firm or custodian named in the advisor’s account paperwork, not directly by Commonwealth.
- The affiliated advisor is the primary point of contact and the one bound by the fiduciary or suitability duties relevant to that relationship.
- Statements, trade confirmations, and advisory agreements a client actually sees will often carry the advisor’s practice name alongside Commonwealth’s, since Commonwealth provides the backend, not the client-facing brand.
- Because many representatives are dually registered as both broker and adviser, the specific role they’re acting in in a given interaction changes which duty of care applies, a distinction worth asking about directly.
Understanding this model matters because it reframes what the enforcement action was really about. The alleged disclosure failures didn’t concern individual client accounts directly, but rather the compensation arrangements sitting one layer up, between Commonwealth and the clearing firm that processed the trades its affiliated advisors placed.
What Did the SEC Allege Against Commonwealth Equity Services?
The SEC’s case centered on a straightforward but consequential claim: Commonwealth allegedly failed to disclose revenue-sharing agreements it maintained with National Financial Services, LLC covering activity between 2014 and 2018. The theory was that Commonwealth received payments tied to client trading and cash sweep activity without adequately disclosing that arrangement to the advisory clients whose assets generated it, a potential violation of the Investment Advisers Act’s disclosure obligations.
The rough sequence of events looks like this:
- 2014 to 2018: The conduct at issue, revenue-sharing payments received in connection with clearing and custody services, occurred during this window.
- Civil enforcement filing: The SEC brought a civil action alleging the firm violated its disclosure duties under the Advisers Act.
- District court proceedings: The matter proceeded through the district court before reaching the appellate stage.
- Appeal to the First Circuit: Commonwealth challenged aspects of the case, and the First Circuit Court of Appeals issued its opinion in 2025.
The core legal question the appellate court confronted was whether the disclosure obligations Commonwealth owed under the Advisers Act extended to the specific revenue-sharing structure at issue, and what standard governs when a conflict tied to a third-party clearing relationship must be surfaced to advisory clients.
The practical upshot for anyone reading the opinion is that remedies in cases like this typically fall into a narrow set of categories: enhanced disclosure requirements going forward, disgorgement of amounts tied to the undisclosed conflict, and injunctive relief barring similar future conduct. The SEC’s own litigation release lays out the agency’s framing of the matter, and reading it alongside the court’s opinion gives a fuller picture than either document alone. If you want a primer on how these releases are structured generally, Murphyslawcrypto’s guide to SEC litigation releases walks through the standard format the agency uses.
This case is also a useful case study in how the SEC’s Division of Enforcement builds disclosure cases against established firms, and how those cases often hinge less on whether a conflict existed than on whether it was adequately surfaced to the people affected by it.
How Do You Verify Commonwealth’s Records Yourself?
You don’t need a securities law background to check most of this firsthand. Here’s the sequence that gets you the fullest picture fastest:
- Search EDGAR by CIK 0000312272 to pull every Form ADV and X-17A-5 filing on record.
- Search FINRA BrokerCheck by CRD 8032 to review registration status, employment history, and any listed disciplinary events.
- Download the current Form ADV Part 2 brochure and Form CRS directly from adviserinfo.sec.gov.
- Cross-check the X-17A-5 filing for auditor identity, fiscal year, and reported financial condition.
- If you work with an affiliated advisor, ask them directly about revenue-sharing arrangements, who holds custody of your assets, and what supervisory office oversees their branch.
Watch for these red flags in your own account paperwork: vague or missing references to third-party compensation, custodian names that don’t match what your advisor told you verbally, or an ADV brochure that hasn’t been updated in over a year despite material changes to fee structures.
Pro Tip: If something in your statements doesn’t match what your advisor described, don’t rely on the SEC’s investor assistance line as your only option. A written complaint to FINRA creates a paper trail, but if real money is at stake, get a private read from counsel before you sign anything else.
For businesses trying to get ahead of similar disclosure gaps before they become enforcement targets, Murphyslawcrypto’s overview of Securities Exchange Act penalties breaks down what’s actually at stake legally when disclosure duties go unmet.
What This Enforcement Case Signals for Disclosure Practice
The legal standard at the heart of this case isn’t exotic. The Investment Advisers Act requires that advisers disclose conflicts of interest that could reasonably affect a client’s judgment, and revenue-sharing tied to clearing or custody relationships is a textbook example of the kind of conflict regulators expect to see spelled out plainly, not buried in dense disclosure language.
Firms that go through an enforcement action like this typically respond in predictable ways: revised ADV brochure language, more granular tracking of third-party payments, and often a broader internal audit of every compensation arrangement that touches client accounts. That’s not optional cleanup. It’s usually a direct condition of settling with the agency or complying with a court’s ruling.
For an individual investor, the real question isn’t whether a firm the size of Commonwealth made a disclosure mistake. It’s whether that mistake changed what you paid or where your money was actually custodied, and whether you have a basis for recovering anything tied to that gap.
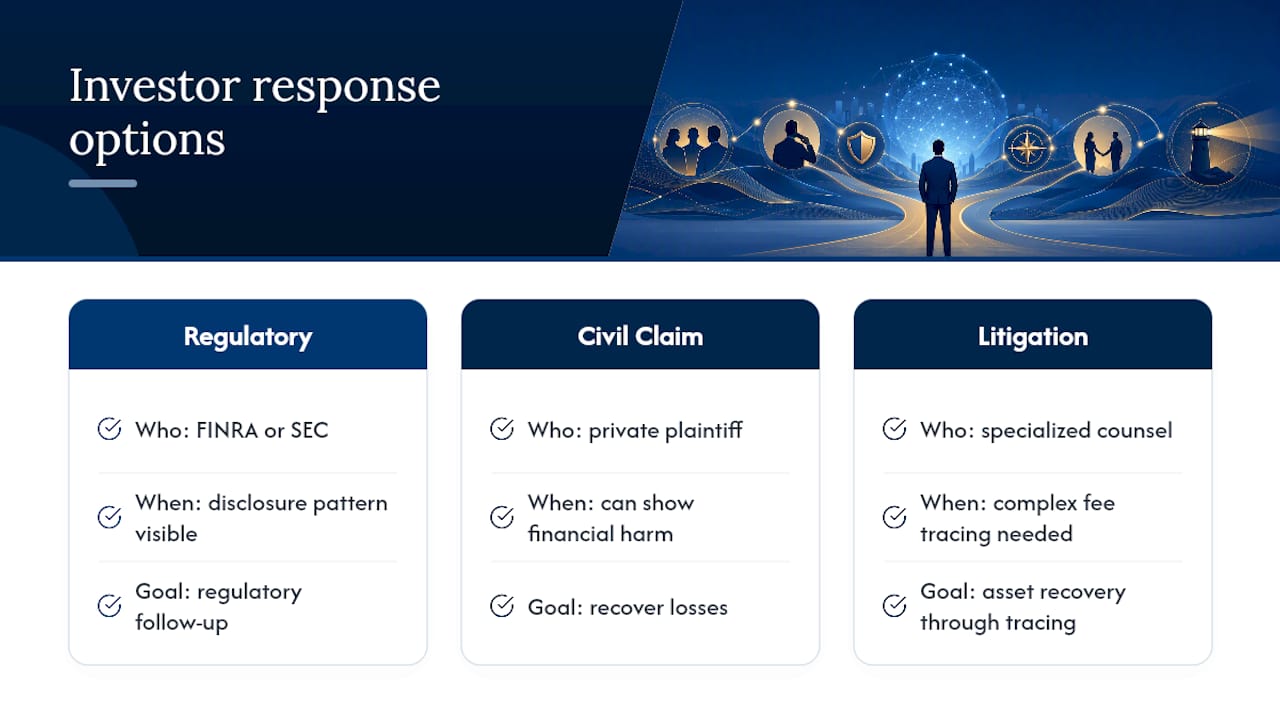
If you find a conflict in your own paperwork that looks similar to what’s described in this case, the path forward generally runs through one of three channels: a complaint to FINRA or the SEC’s investor assistance office for regulatory follow-up, a private civil claim if you can show financial harm, or, for the kind of forensic asset tracing that untangles years of undisclosed fee flows, engaging litigation counsel who has actually handled recovery cases at this scale. General compliance resources on annual LLC compliance obligations are useful background, but they won’t substitute for a case-specific legal review once real money is on the line.
Ready to Look Into Your Own Situation?
Reading a court opinion is one thing. Figuring out whether it applies to your account, your advisor, or your losses is another matter entirely, and it’s usually where people get stuck. Murphy’s Law was built by litigators who’ve handled major disclosure and fraud cases in the digital asset space, and the same forensic and legal skill set applies whenever a client’s money moved through a relationship that wasn’t fully disclosed.
If your statements show custody arrangements or fees that don’t match what you were told, or you’re an advisor trying to understand your own supervisory exposure, Murphy’s Law’s crypto fraud recovery services can help you figure out whether you have a claim worth pursuing and what that process actually looks like.
A Verification-First Read on the Commonwealth Case
The research here supports a fairly narrow but important judgment: this case isn’t really about whether Commonwealth is a legitimate firm, it plainly is, but about whether a specific compensation arrangement got adequately disclosed to the people whose money generated it. That distinction gets lost in a lot of secondhand coverage that treats any SEC enforcement action as proof of broader misconduct.
Where conventional advice falls short is in telling readers to just “check if a firm is registered” and stop there. Registration status answers almost nothing about whether your specific fee structure or custody arrangement carries an undisclosed conflict. The ADV brochure and Form CRS do that work, and most investors never open either one.
If you take one thing from this case, prioritize reading your own advisor’s disclosure documents before assuming an enforcement action three years old has nothing to do with you. Then, if something doesn’t add up, get a professional read rather than guessing.
— Mark
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- EDGAR: Company filings for CIVK 0000312272 (Commonwealth Equity Services, LLC)
- Securities and Exchange Commission v. Commonwealth Equity Services, LLC (1st Cir. 2025) — Justia
- COMMONWEALTH FINANCIAL NETWORK – BrokerCheck
FAQ
What happened to Commonwealth Financial Services?
Commonwealth Equity Services, LLC (d/b/a Commonwealth Financial Network) remains an active, registered broker-dealer and investment adviser. The firm faced an SEC enforcement action over undisclosed revenue-sharing conflicts from 2014 to 2018, which reached the First Circuit Court of Appeals in 2025.
Is Commonwealth the same as Fidelity?
No. Commonwealth is an independent broker-dealer and RIA that supports affiliated financial advisors, while Fidelity operates its own separate brokerage, custody, and asset management businesses; the two are unrelated corporate entities, though Commonwealth’s clearing relationships may involve other custodians entirely.
Is Commonwealth Financial Network legitimate?
Yes, it’s a registered, actively operating broker-dealer and investment adviser with a public filing history on EDGAR and BrokerCheck. Legitimacy as a registered entity is separate from whether any specific disclosure practice, like the one at issue in its 2025 appellate case, held up to scrutiny.
Who owns Commonwealth Financial Services?
Commonwealth Financial Network operates as Commonwealth Equity Services, LLC, and detailed ownership structure is disclosed in its Form ADV Part 1 filings available on EDGAR and adviserinfo.sec.gov, rather than through any single named parent company reported in public materials.
What was the core allegation in the SEC’s case against Commonwealth?
The SEC alleged Commonwealth failed to adequately disclose revenue-sharing payments it received from National Financial Services, LLC tied to client trading activity between 2014 and 2018, a potential violation of disclosure duties under the Investment Advisers Act.