
An investment contract exists when a person invests money in a common enterprise and reasonably expects profits derived from the efforts of others. That is the Howey test, established by the U.S. Supreme Court in SEC v. W. J. Howey Co., 328 U.S. 293 (1946), and it remains the controlling standard under Securities Act §2(a)(1) for determining whether any agreement, transaction, or scheme qualifies as a security subject to federal regulation.
Three practical implications follow immediately:
- Labels do not control. Calling something a “loan,” a “membership interest,” or a “utility token” does not remove it from securities law if the economic substance satisfies Howey. The SEC has consistently emphasized that analysis looks to economic reality, not the name on the document.
- Promoter promises and profit expectations are the live wires. Marketing materials, pitch decks, and roadmaps that emphasize investor returns or issuer-driven value creation are among the strongest indicators that an arrangement is an investment contract.
- Act before you offer. If you are raising capital, issuing tokens, or structuring a revenue-sharing deal, the time to conduct a Howey analysis is before the first dollar changes hands, not after the SEC sends a subpoena.
Key Takeaways
An investment contract is defined by economic substance, not by the label on the document: if the Howey test is satisfied, federal securities law applies regardless of how the parties describe the arrangement.
| Point | Details |
|---|---|
| Howey controls the analysis | All four prongs must be assessed: investment of money, common enterprise, profit expectation, and reliance on others’ efforts. |
| Labels do not determine status | Calling an instrument a “loan,” “token,” or “membership interest” does not exempt it from securities law if economic substance satisfies Howey. |
| Marketing creates profit expectations | Pitch decks, whitepapers, and social media posts that emphasize returns can establish the profit-expectation prong even when the contract itself is silent. |
| Crypto separation requires a factual record | A token moves away from investment-contract treatment only when decentralization is genuine and documented, not merely claimed. |
| Murphyslawcrypto provides pre-offer review and recovery | The firm handles Howey analysis, SEC engagement, and litigation for issuers and investors across traditional and crypto offerings. |
Table of Contents
- What is an investment contract under U.S. securities law?
- How courts and the SEC apply Howey to real fact patterns
- Which deal structures commonly raise investment-contract issues?
- What should a well-drafted investment agreement include?
- What are the regulatory consequences of getting this wrong?
- How does Howey apply to crypto tokens and digital assets?
- Frontline lessons: drafting mistakes that create enforcement exposure
- When should you hire securities counsel?
- The Howey test is necessary but not sufficient
- Murphyslawcrypto: securities counsel for issuers and investors
- Sources
- FAQ
What is an investment contract under U.S. securities law?
The statutory starting point is 15 U.S.C. §77b, which lists “investment contract” as one of the enumerated instruments included in the definition of “security.” Congress did not define the phrase in the statute, leaving courts to supply the meaning. The Supreme Court did exactly that in Howey.
The Court’s one-sentence test has endured for nearly eighty years:
Courts have since softened “solely” to “predominantly,” recognizing that investors often play some minor role, but the four core components remain intact:
- Investment of money: A contribution of capital or something of value.
- Common enterprise: Investor fortunes are tied to each other or to the promoter (horizontal or vertical commonality, depending on the circuit).
- Expectation of profits: The investor anticipates a financial return, whether through dividends, capital appreciation, or revenue sharing.
- Efforts of others: Returns depend primarily on the managerial or entrepreneurial efforts of the promoter or a third party, not the investor.
The judicial purpose behind this four-part framework is flexibility. Congress wanted a definition broad enough to capture novel schemes that clever promoters might design to evade a narrower rule. Scholars have argued that the original public meaning of “investment contract” required a genuine quid pro quo: an investor’s money exchanged for a contractual right to receive a share of profits generated by the offeror’s efforts. Under that reading, a pure asset purchase, such as buying a painting, is not an investment contract because the buyer receives the artwork itself rather than a contractual profit share. That distinction matters in practice when courts evaluate NFTs, collectibles, and commodity-adjacent crypto assets.
The SEC’s interpretive work has extended Howey into successive waves of financial innovation. The DAO Report applied Howey to token offerings and found that certain DAO tokens were securities because purchasers expected profits from the managerial efforts of the DAO’s founders. The SEC’s 2026 interpretive release carries that reasoning forward, applying Howey to a broader range of crypto assets and clarifying when a non-security asset becomes subject to an investment contract because of issuer representations and continued managerial efforts.
How courts and the SEC apply Howey to real fact patterns
The original Howey fact pattern
W. J. Howey Co. sold parcels of a Florida citrus grove to the public, then offered buyers a service contract under which Howey would cultivate, harvest, and market the fruit. Buyers had no farming expertise and no practical ability to manage the land themselves. The Court held the combined land-plus-service-contract arrangement was an investment contract because purchasers expected profits from Howey’s agricultural efforts, not their own.
The lesson: separating an asset sale from a service contract does not defeat securities-law treatment if the two are economically intertwined and the investor’s return depends on the seller’s ongoing work.
The DAO Report and token offerings
The SEC’s staff applied Howey to DAO tokens and concluded they were securities. DAO token holders invested Ether in a common enterprise, expected returns from the DAO’s investment activities, and relied on the managerial efforts of “Curators” who controlled which proposals received funding. The fact that the arrangement used smart contracts and blockchain technology did not change the economic substance.
Patterns that tilt toward investment-contract treatment
- Promoter or issuer retains ongoing managerial control over the enterprise generating returns.
- Marketing materials, whitepapers, or pitch decks emphasize financial returns or token price appreciation.
- A secondary market exists or is anticipated, creating resale profit expectations.
- Investors have no meaningful ability to influence outcomes through their own efforts.
- Revenue or profit sharing is tied to the issuer’s operational performance.
Patterns that weigh against investment-contract treatment
- Purchasers acquire a token or product primarily for its consumption or utility value, not financial return.
- The protocol is genuinely decentralized: no single party controls development, treasury, or governance.
- There is no contractual right to profits; the buyer simply owns an asset whose market price may fluctuate.
- The issuer has made no representations about future value or managerial efforts.
The SEC’s 2026 interpretive release addresses secondary-market transactions specifically, explaining that even a non-security crypto asset can become subject to an investment contract if the issuer continues to make representations about future development and investors in the secondary market reasonably rely on those representations. That is a significant expansion of the analysis beyond the initial offering.
Which deal structures commonly raise investment-contract issues?
Most capital-raising transactions involve at least one instrument that could satisfy Howey under the right facts. The key is identifying which features create the exposure.
- Convertible notes: A note that converts to equity at a future financing round is often treated as a security because the investor’s return depends on the company’s performance and the promoter’s efforts to grow the business. The conversion mechanics, interest rate, and valuation cap all affect the analysis.
- SAFEs (Simple Agreements for Future Equity): SAFEs grant investors the right to receive equity upon a triggering event. Courts and the SEC generally treat SAFEs as securities because the investor’s return is entirely contingent on the issuer’s future fundraising and operational success.
- Equity purchase agreements: Direct equity purchases are paradigmatic securities transactions. The investor acquires an ownership stake whose value depends on the company’s performance, satisfying all four Howey prongs.
- Revenue-sharing agreements: These arrangements promise investors a percentage of future revenue. Whether they are securities depends on whether the investor’s return is tied to the promoter’s managerial efforts. A passive investor receiving a revenue share from a business run entirely by the issuer almost certainly holds a security.
- Limited partnership interests: LP interests are textbook investment contracts. The limited partner contributes capital, shares in profits, and relies on the general partner’s management. The SEC has never seriously contested this classification.
- Token and coin offerings: The analysis turns on the specific facts of each offering. A token marketed with promises of future platform development and price appreciation, sold to passive investors who expect returns from the issuer’s efforts, is almost certainly an investment contract. A token with immediate, genuine utility and no issuer profit promises occupies a different position.
Real-world clause language for these instruments appears in public EDGAR investment-agreement exhibits, which show how purchase mechanics, admission rights, and the relationship between an investment agreement and a partnership agreement are structured in practice. Reviewing EDGAR Exhibit 10.27 filings provides additional clause-level detail on how practitioners draft investor-agreement mechanics in public companies.
What should a well-drafted investment agreement include?
A well-structured investor agreement finalizes the term sheet and governs the relationship between issuer and investor from closing through exit. The following checklist covers the clauses that matter most.
Core drafting checklist
- Transaction terms: Investment amount, type of security (equity, debt, convertible instrument), price per unit or share, and closing conditions.
- Investor rights: Information rights (financial statements, board minutes), inspection rights, and pro-rata participation in future rounds.
- Governance and board controls: Board composition, observer rights, protective provisions requiring investor consent for major decisions (new equity issuances, asset sales, charter amendments).
- Transfer restrictions: Lock-up periods, right of first refusal, co-sale rights, and drag-along provisions. Transfer restrictions also affect the Howey analysis: tighter restrictions reduce secondary-market profit expectations.
- Conversion mechanics: For convertible instruments, specify the conversion trigger, valuation cap, discount rate, and most-favored-nation provisions.
- Liquidation preferences: Non-participating versus participating preferred, preference multiples, and waterfall order.
- Anti-dilution protection: Broad-based weighted-average versus narrow-based weighted-average versus full ratchet. Full ratchet is rare and heavily founder-unfavorable.
- Representations and warranties: Issuer representations about capitalization, intellectual property ownership, absence of litigation, and compliance with law; investor representations about accredited-investor status and investment intent.
- Indemnification: Scope, survival periods, and caps on liability.
- Dispute resolution: Arbitration versus litigation, governing law, and venue selection.
- Confidentiality: Scope of confidential information, carve-outs for required disclosures, and duration.
- Conditions precedent: Regulatory approvals, third-party consents, and legal opinions required before closing.
Clause language and regulatory exposure
How you draft certain clauses can directly affect whether the arrangement looks like an investment contract. Contrast that with a fixed-return note that pays a stated interest rate regardless of company performance: the latter is more likely to be analyzed as a debt instrument than an investment contract, though the full facts still govern.
Marketing language matters just as much as contract language. A pitch deck that says “token holders will benefit from the growth of our ecosystem” creates a profit expectation that survives even a carefully drafted agreement that omits profit promises. Courts look at the totality of the offering, not just the four corners of the contract.
Pro Tip: Before finalizing any offering document, run every piece of investor-facing communication, including emails, social media posts, and presentation slides, through a Howey checklist. Representations made outside the contract can be just as determinative as the contract terms themselves.
Key negotiation levers
- Anti-dilution: Broad-based weighted-average is the market standard for early-stage deals; push back on full ratchet.
- Participation rights: Participating preferred gives investors their liquidation preference plus a pro-rata share of remaining proceeds; non-participating preferred forces a choice. Founders should understand the economic difference before signing.
- Protective covenants: Investors often seek veto rights over new equity issuances, debt above a threshold, and changes to the company’s business. Negotiate these carefully; overly broad protective covenants can paralyze future fundraising.
- Founder vesting: Investors routinely require founders to re-vest equity over a four-year schedule with a one-year cliff. This protects investors if a founder departs early but also creates founder-control implications worth understanding before you agree.
What are the regulatory consequences of getting this wrong?
If an offer or sale of securities is not registered with the SEC and no exemption applies, the consequences are serious. Section 5 of the Securities Act prohibits unregistered offers and sales of securities. Violations expose issuers to civil liability under Section 12(a)(1), which gives investors the right to rescind the transaction and recover their investment plus interest. The SEC can also bring enforcement actions seeking disgorgement of profits, civil monetary penalties, and injunctions against future violations.
Common exemptions and when they apply
Most private offerings rely on one of the following exemptions rather than full registration:
- Regulation D, Rule 506(b): Permits sales to up to 35 non-accredited but sophisticated investors and an unlimited number of accredited investors, with no general solicitation. This is the most commonly used private-placement exemption.
- Regulation D, Rule 506©: Permits general solicitation and advertising, but all purchasers must be verified accredited investors. Verification requires more than a self-certification checkbox.
- Regulation Crowdfunding (Reg CF): Permits offerings up to $5 million in a 12-month period through an SEC-registered funding portal. Investor limits apply based on income and net worth.
- Rule 144A: Permits resales of restricted securities to qualified institutional buyers (QIBs). This is a resale exemption, not an offering exemption, and it requires the securities to be eligible for resale to QIBs.
- Section 4(a)(1): Exempts transactions by persons other than issuers, underwriters, or dealers. Ordinary investors reselling securities in the secondary market typically rely on this exemption.
| Exemption | Who Can Invest | General Solicitation | Offering Limit |
|---|---|---|---|
| Rule 506(b) | Accredited + up to 35 sophisticated | No | None |
| Rule 506© | Verified accredited only | Yes | None |
| Reg CF | General public (with limits) | Yes | $5 million per 12 months |
| Rule 144A | Qualified institutional buyers | Yes (to QIBs) | None |
Practical mitigation steps
- Conduct a Howey analysis before structuring any capital raise.
- Prepare an offering memorandum or disclosure document appropriate to the exemption used.
- Implement accredited-investor verification procedures that go beyond self-certification for Rule 506© offerings.
- Include transfer restrictions in the agreement and on any certificates or digital records to limit secondary-market activity.
- Maintain a complete record of investor communications, including pitch materials and emails, in case of an SEC inquiry.
- For crypto offerings, consider SEC crypto regulations and parallel CFTC jurisdiction before launch.
SEC enforcement in the crypto space has produced disgorgement orders, civil penalties, and injunctions in cases involving unregistered token offerings, fraudulent ICOs, and unregistered broker-dealer activity. The practical business impact of a registration violation extends beyond the legal penalty: rescission liability can exceed the original offering proceeds if the investment has declined in value, and an injunction can bar the issuer from future capital markets activity.
How does Howey apply to crypto tokens and digital assets?
The SEC’s position, confirmed in its 2026 interpretive release, is that Howey applies to crypto assets using the same four-prong analysis it applies to any other instrument. The release classifies crypto assets into functional categories and explains when a non-security asset becomes subject to an investment contract because of issuer promises and continued reliance on managerial efforts.
The “efforts of others” prong in crypto
For most token projects, the live question is whether purchasers reasonably expect the issuer or a core development team to continue essential managerial efforts. A project that is genuinely decentralized, where no single party controls development, treasury, or governance, presents a weaker case for securities treatment because the “efforts of others” prong is harder to satisfy. But decentralization is a moving target. A project that launches with a centralized team and later claims decentralization may still face securities-law exposure for its initial offering period.
How a token can separate from investment-contract treatment
A token can move away from securities treatment as a project matures, but the separation requires more than a governance vote or a whitepaper update. The SEC looks at whether:
- The issuer has ceased making representations about future development or value.
- Purchasers in the secondary market are buying for consumption or utility, not financial return.
- No single party retains meaningful control over the protocol’s direction or treasury.
- The token’s value is no longer primarily tied to the issuer’s ongoing efforts.
Secondary-market holders present a distinct analytical challenge. Even if the initial offering was exempt or non-securities, secondary-market purchasers who buy based on issuer representations about future development may hold investment contracts. The 2026 interpretive release addresses this directly.
Product-design and go-to-market steps to reduce exposure
- Limit resale at launch through transfer restrictions and lockup periods.
- Avoid making any representations about token price, future value, or ecosystem growth in marketing materials.
- Design distribution mechanisms that reward genuine use rather than speculation (e.g., earn-through-use rather than purchase-to-hold).
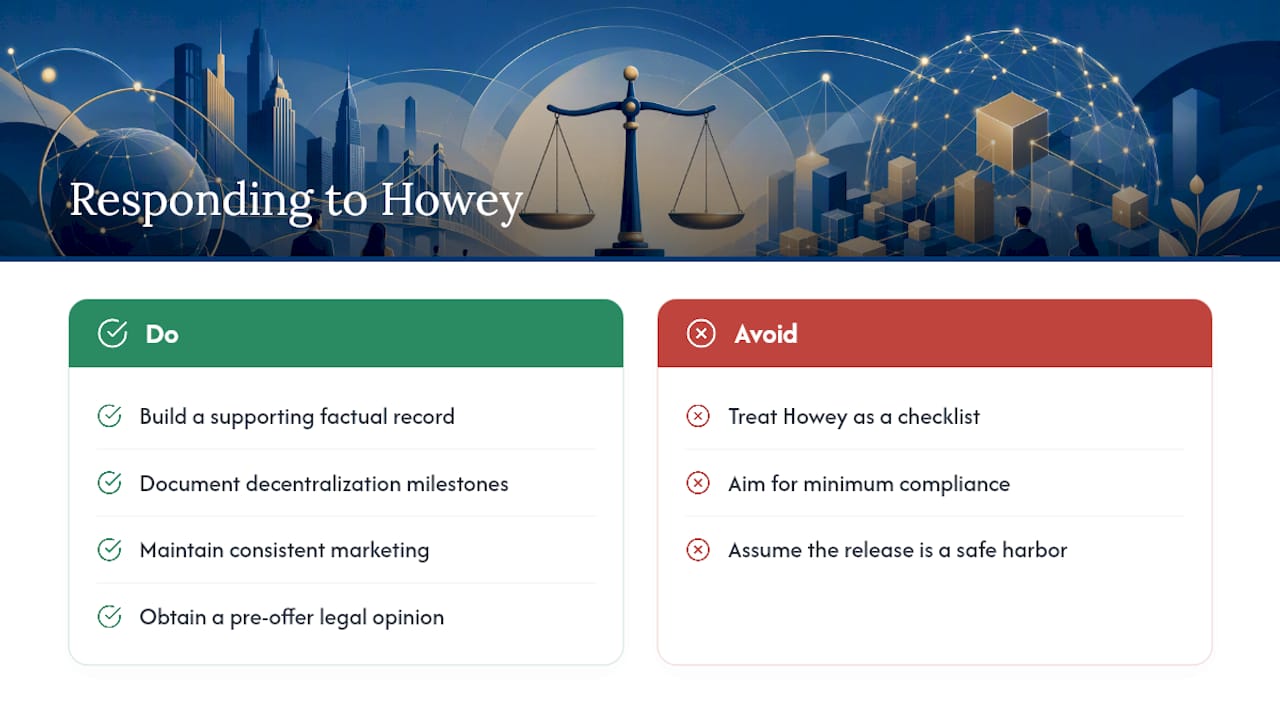
- Document decentralization milestones: governance transitions, treasury diversification, and reduction of core-team control over protocol parameters.
- Engage crypto securities law counsel before the token design is finalized, not after the whitepaper is published.
Pro Tip: The risk profile of a token offering changes at each stage of the project lifecycle. A token sold in a pre-launch private sale carries the highest securities-law risk because purchasers are entirely dependent on the founding team’s future efforts. A token with a live, functional protocol and active third-party developers occupies a meaningfully different position. Document each decentralization milestone contemporaneously; retroactive documentation is far less persuasive to regulators.
Frontline lessons: drafting mistakes that create enforcement exposure
Practitioners who work through the full arc of a securities matter, from pre-offer structuring through SEC inquiry and litigation, see the same categories of mistakes repeatedly. None of them are exotic.
Ambiguous conversion mechanics
A convertible note or SAFE with a vague conversion trigger creates two problems simultaneously. First, it invites a dispute between the issuer and investor about when and how conversion occurs. Second, ambiguous mechanics can make it harder to establish that the instrument was a bona fide debt obligation rather than an equity security, which affects both the Howey analysis and the applicable exemption.
Poor transfer-restriction drafting
Transfer restrictions serve a dual purpose: they satisfy conditions of the exemption used (particularly Rule 506(b)) and they reduce secondary-market profit expectations under Howey. Restrictions that are technically present but practically unenforceable, because they lack a stop-transfer instruction on the record or a corresponding legend on the instrument, provide neither benefit.
Overly broad marketing promises
This pattern appears in SEC enforcement actions across both traditional private placements and token offerings. The remedy is a pre-offer marketing review that applies the same Howey checklist to every investor-facing communication.
Inadequate accredited-investor verification
Rule 506© permits general solicitation but requires issuers to take reasonable steps to verify that all purchasers are accredited investors. A checkbox on a subscription agreement is not verification. Reasonable steps include reviewing tax returns, W-2s, bank statements, or obtaining a written confirmation from a licensed attorney, CPA, or registered broker-dealer.
Remediation steps for mid-deal or post-offer situations
- Preserve all documents immediately: contracts, pitch materials, investor communications, and internal emails.
- Assess whether a voluntary disclosure to the SEC is appropriate given the facts and the applicable exemption.
- Consider a remedial repurchase offer under Section 3(a)(9) or a rescission offer to affected investors.
- Engage early regulatory counsel before making any public statement about the issue.
Murphyslawcrypto assists issuers and investors at each of these stages: pre-offer compliance review, SEC engagement and response, and litigation or recovery work when a transaction has already gone wrong.
When should you hire securities counsel?
Hire counsel before any of the following occur: you solicit funds from more than a handful of people, a secondary market for your instrument exists or is anticipated, your marketing materials emphasize investor returns, or you receive any communication from the SEC or FINRA.
Clear indicators that you need counsel now
- You plan to raise capital from investors who are not your immediate family or close personal contacts.
- Your offering involves a token, coin, or digital asset with any secondary-market trading.
- Investors in your deal expect returns primarily from your efforts, not their own.
- You have already made offers or sales without a Howey analysis or exemption review.
- You have received an SEC subpoena, comment letter, or informal inquiry.
- A co-founder, employee, or investor has raised concerns about the legality of the offering.
Documents to bring to your first meeting
- Term sheet or letter of intent.
- Draft or executed investment agreement, subscription agreement, or SAFE.
- All pitch materials, including slide decks, whitepapers, and investor emails.
- Cap table showing current and post-offering ownership.
- Prior investor agreements and any side letters.
- Marketing copy, social media posts, and any public statements about the offering.
- Tokenomics documentation and project roadmap (for crypto offerings).
- Audited or reviewed financial statements, if available.
- Any prior legal opinions or compliance memos related to the offering.
Questions to ask prospective securities counsel
- Have you handled SEC enforcement matters involving unregistered offerings?
- What exemption do you recommend for this offering, and why?
- Will you review our marketing materials as well as the contract?
- What does your pre-offer compliance memo cover, and how long does it take?
- If the SEC contacts us, what is your response protocol?
The benefits of engaging counsel early are not abstract: a pre-offer compliance review typically costs a fraction of the legal fees required to respond to an SEC investigation, and it eliminates the rescission liability that attaches to an unregistered offering.
The Howey test is necessary but not sufficient
The Howey test is the right starting point, but treating it as a checklist to be cleared rather than a framework for understanding economic substance is where issuers get into trouble. Courts and the SEC do not evaluate the four prongs in isolation. They look at the totality of the offering: who is being solicited, what they are being told, what they reasonably expect, and who actually controls the enterprise generating returns.
The original-meaning scholarship on “investment contract” is worth taking seriously. The argument that a genuine quid pro quo, an investor’s money exchanged for a contractual right to profits, is necessary for securities treatment has real implications for how practitioners should structure instruments. An arrangement that gives investors a contractual right to a revenue share is analytically different from one that gives them a commodity whose market price may rise. Both may satisfy Howey under the right facts, but the drafting choices that distinguish them are not trivial.
For crypto issuers, the 2026 interpretive release should be read as a signal, not a safe harbor. The SEC has not retreated from Howey; it has applied it with greater specificity to a wider range of instruments. The practical response is not to find the minimum compliance threshold but to build a factual record that genuinely supports the position you are taking. That means contemporaneous documentation of decentralization milestones, consistent marketing discipline, and a pre-offer legal opinion that addresses the specific facts of your offering.
Murphyslawcrypto: securities counsel for issuers and investors
When an investment agreement raises securities-law questions, or when an offering has already gone wrong, the difference between a licensed law firm with courtroom experience and a generic compliance vendor is the difference between a defensible position and an exposed one.
Murphyslawcrypto, founded by Liam Murphy, Esq. (Penn Law, formerly Paul Hastings, Selendy Gay, and McKool Smith), provides pre-offer compliance reviews, Howey analysis memos, SEC engagement and response, and crypto fraud recovery litigation for investors who participated in offerings that turned out to be unregistered securities. Liam has litigated matters involving Celsius, Terraform Labs, and BitMEX, and the firm maintains an active docket of fraud and recovery cases. If you are structuring an offering, reviewing an investment agreement, or facing an SEC inquiry, the first step is a consultation. Bring your term sheet, pitch materials, and any investor communications. Contact Murphyslawcrypto at Murphyslawcrypto to schedule that conversation.
Sources
The following primary authorities are the foundation for the analysis in this article. Each source adds something distinct.
- Application of the Federal Securities Laws to Certain Types of Crypto Assets and Certain Transactions Involving Crypto Assets
- SEC v. W. J. Howey Co., 328 U.S. 293 (1946)
- The Original Public Meaning of Investment Contract
- 15 U.S.C. §77b (Definition of “Security”) — Legal Information Institute
- How Small Businesses Can Write a Strong Investor Agreement
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
What is an investment contract under U.S. law?
An investment contract is any arrangement in which a person invests money in a common enterprise and expects profits primarily from the efforts of others, as defined by the Supreme Court in SEC v. W. J. Howey Co. and codified within the definition of “security” at Securities Act §2(a)(1).
Can you give me an example of an investment contract?
The original Howey example is instructive: investors purchased citrus grove parcels and signed service contracts giving Howey Co. full control over cultivation and sales. Courts and the SEC have since applied the same analysis to limited partnership interests, SAFEs, revenue-sharing agreements, and token offerings where purchasers rely on the issuer’s ongoing development efforts.
What are the four types of contracts?
Contract law recognizes express, implied, unilateral, and bilateral contracts as general categories, but that taxonomy is distinct from the securities-law question of whether a specific contract is an “investment contract” under Howey. The Howey analysis applies regardless of which general contract type the arrangement takes.
What are the biggest risks in an investment contract?
The primary risks are regulatory: an unregistered offering that satisfies Howey exposes issuers to Section 12(a)(1) rescission liability, SEC enforcement seeking disgorgement and civil penalties, and potential injunctions against future capital-markets activity. Investors face the risk of participating in an unlawful offering with limited secondary-market liquidity and uncertain legal recourse if the issuer fails.
When should I hire a securities lawyer for an investment agreement?
Hire counsel before you solicit any investor, before you publish any marketing materials, and before you finalize the agreement structure. If you have already made offers or sales without a Howey analysis, contact counsel immediately to assess rescission exposure and remediation options.