
Insider trading is lawful when it complies with Section 10(b) of the Securities Exchange Act and SEC Rule 10b-5, most commonly through a properly structured Rule 10b5-1 trading plan and timely Form 4 disclosure. It becomes a federal crime the moment someone trades on material, nonpublic information while breaching a duty of trust, or tips someone else who does. There is no gray area once those elements line up, only a narrow set of protected paths around them.
Three things to hold onto before you read further:
- Lawful routes: trading under a preexisting 10b5-1 plan, acting on public information, or filing Form 4 on time all keep insiders on the right side of the law.
- Illegal triggers: trading (or tipping someone who trades) on material, nonpublic information obtained through a breach of duty or misappropriation is what turns a trade into a federal case.
- When in doubt, don’t guess. If a trade touches confidential deal information, layoffs, earnings surprises, or a pending SEC inquiry, talk to a securities lawyer before you place the order.
Key Takeaways
Legal insider trading depends on three factors working together: no material nonpublic information, no breach of duty, and full compliance with SEC reporting rules.
| Point | Details |
|---|---|
| Core legal test | Trading is illegal only when information is material, nonpublic, and tied to a breach of duty or misappropriation. |
| Safe harbor exists | A properly adopted, unmodified Rule 10b5-1 plan provides an affirmative defense against insider-trading claims. |
| Reporting matters | Form 4 must be filed within two business days of a covered transaction by officers, directors, and major shareholders. |
| Penalties stack | SEC civil penalties can reach three times profit gained, separate from any DOJ criminal fines or prison time. |
| Get counsel early | Murphy’s Law Crypto handles investigations, SEC/DOJ response, and compliance drafting for individuals facing exposure. |
Table of Contents
- What Legally Makes Insider Trading Illegal: the Elements and Tests
- How Insiders Can Trade Legally: Compliance Routes and Practical Steps
- Primary Statutes, SEC Rules, and Precedent Cases That Define the Law
- Penalties, Enforcement Agencies, and Typical Remedies
- How Prosecutions and Proofs Work: Evidence Prosecutors Use and Common Defenses
- When to Get a Securities Lawyer and What They Will Do for You
- Where Enforcement Is Headed, and Why Caution Still Wins
- If You Need Help: Legal Support for Insider Trading Matters
- Primary Sources and Recommended Reading
- Sources
- FAQ
What Legally Makes Insider Trading Illegal: the Elements and Tests
The SEC and federal courts look for three things: material information, nonpublic status, and a breach of duty. Information is material if a reasonable investor would consider it important to a buy, sell, or hold decision, a merger term sheet, an unreleased earnings miss, an FDA rejection. It is nonpublic if it hasn’t been disseminated broadly enough for the market to absorb it. Neither element alone is illegal. Trading on both, while violating a duty, is.
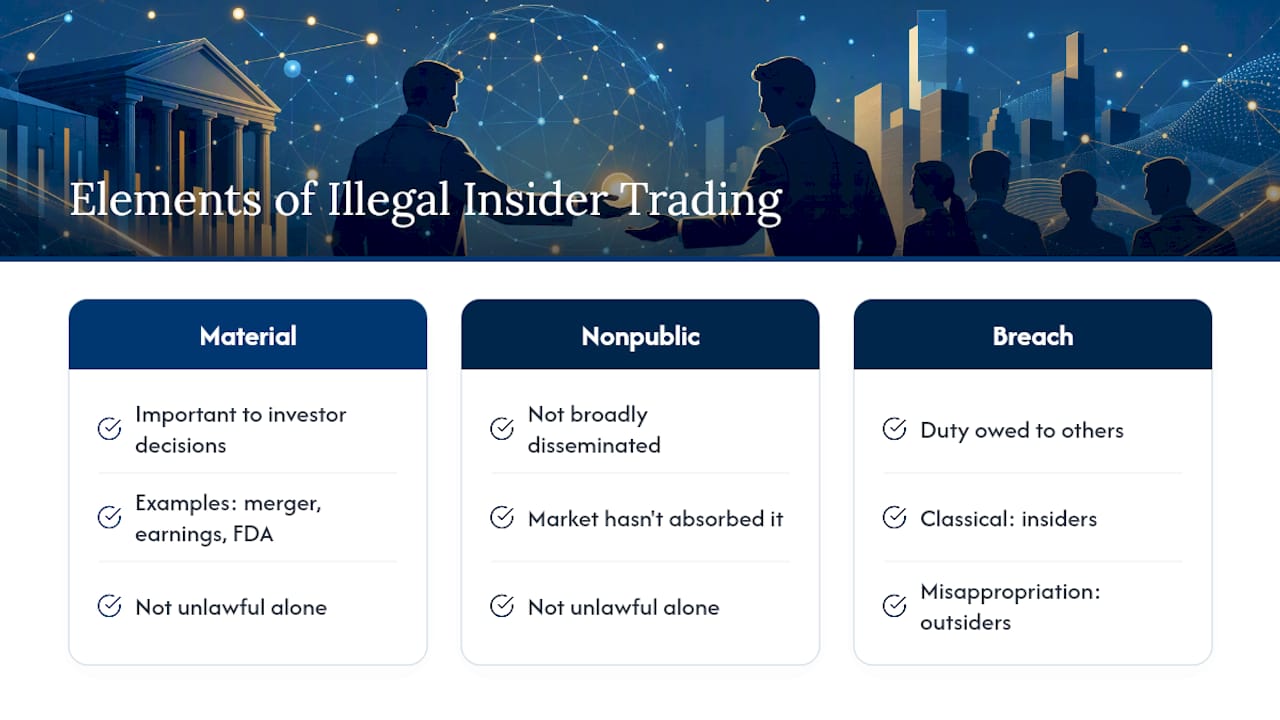
That duty comes in two flavors. The classical theory, from Chiarella v. United States, holds that a corporate insider (officer, director, major shareholder) who trades on confidential company information breaches a duty owed directly to shareholders. The misappropriation theory, cemented in United States v. O’Hagan, extends liability to outsiders, lawyers, bankers, consultants, who steal confidential information from a source they owe a duty to, even if they owe no duty to the counterparty on the other side of the trade.
Then there’s tipping. Under Dirks v. SEC, a tippee is only liable if they knew (or should have known) the tipper breached a duty and got a personal benefit in return, cash, a reciprocal favor, even reputational gain among friends. Two later cases refined that standard without gutting it:
United States v. Newman narrowed personal-benefit liability by requiring proof the tippee knew about the benefit exchanged for the tip.
Salman v. United States restored ground lost in Newman, holding that gifting inside information to a relative counts as a personal benefit on its own.
The takeaway for non-insiders: receiving a tip from a friend or relative doesn’t automatically expose you, but trading on it usually does once you know or should have known the source had no business sharing it.
How Insiders Can Trade Legally: Compliance Routes and Practical Steps
Rule 10b5-1 exists precisely so insiders aren’t frozen out of their own company’s stock. The SEC’s 2022 amendments confirm the plan provides an affirmative defense when it’s adopted and followed correctly. Here’s the process:
- Adopt the plan while clean. You must establish it at a time when you are not in possession of material nonpublic information, and you must act in good faith throughout.
- Make it binding, not discretionary. The plan needs to specify exact amounts, prices, and dates, or delegate trading decisions to an independent third party through a binding formula.
- Don’t touch it afterward. Modifying the plan, canceling trades selectively, or layering in a second overlapping plan is exactly what invites SEC scrutiny, regulatory text under 17 CFR § 240.10b5-1 limits how and when plans can change.
- File Form 4 on time. Officers, directors, and 10%-plus owners must report covered transactions to the SEC within two business days of execution.
Companies layer additional controls on top: preclearance requirements before any trade, blackout windows around earnings and major announcements, and internal logs documenting who approved what and when.
Pro Tip: Use an independent third-party administrator to execute your 10b5-1 plan, and keep a written record of exactly who adopted it and on what date. That paper trail is often the difference between a clean affirmative defense and a plan the SEC picks apart line by line.
Primary Statutes, SEC Rules, and Precedent Cases That Define the Law
There’s no single federal statute that says “insider trading is illegal.” The Congressional Research Service confirms the law has been built almost entirely through SEC rulemaking and judicial interpretation of a broad antifraud provision. That’s why case law carries so much weight here.
- Section 10(b) of the Exchange Act bars fraud “in connection with the purchase or sale of any security,” the broad statutory hook everything else hangs on.
- SEC Rule 10b-5 operationalizes Section 10(b), prohibiting deceptive devices and material misstatements.
- Rule 10b5-1 creates the affirmative defense for prearranged trading plans.
- Rule 10b5-2 extends misappropriation liability to certain nonbusiness relationships, family and personal, where confidence was reasonably expected.
- Rule 14e-3 separately bans trading on nonpublic information about a pending tender offer, without requiring proof of a fiduciary breach.
- 15 U.S.C. §78u-1 authorizes civil penalties up to three times profit gained or loss avoided.
- The STOCK Act confirms members of Congress and federal employees owe duties of trust regarding information obtained through office, closing any perceived carve-out.
Chiarella, Dirks, O’Hagan, Newman, and Salman remain the five cases every securities lawyer cites when mapping a client’s exposure, because together they define who owes a duty, to whom, and what counts as breaching it.
Penalties, Enforcement Agencies, and Typical Remedies
Two agencies bring the overwhelming majority of insider-trading actions, and they don’t always move in tandem.
- The SEC pursues civil enforcement. Remedies include disgorgement of ill-gotten gains and civil penalties that can reach three times the profit gained or loss avoided under federal law.
- The DOJ pursues criminal prosecution. Convictions can carry prison time and separate criminal fines, layered on top of, not instead of, SEC civil penalties.
State securities regulators and self-regulatory organizations like FINRA can also open parallel inquiries, particularly when a trade touches a broker-dealer’s surveillance systems.
The exposure is compounding, not either/or. A single trade can trigger an SEC civil case, a DOJ criminal indictment, and a FINRA referral simultaneously, with the treble civil penalty calculated independently of any criminal fine or sentence a court imposes.
How Prosecutions and Proofs Work: Evidence Prosecutors Use and Common Defenses
Insider-trading cases rarely turn on a smoking-gun confession. They turn on timing and paper trails.
- Trading records showing purchases or sales suspiciously close to a material announcement.
- Communications, emails, texts, Slack messages, between a tipper and tippee.
- Timestamped research or calendar entries that contradict a claimed independent trading rationale.
- Witness testimony connecting a tip to a personal benefit.
Common defenses include showing the trade relied on public information, was executed under a validly adopted 10b5-1 plan, or that the information at issue wasn’t actually material. Lack of knowledge matters too, if you genuinely didn’t know your source breached a duty, that can defeat tippee liability under the Dirks framework.
The government generally has to connect three dots: that the information was material and nonpublic, that someone breached a duty in sharing or trading on it, and that the trader knew or should have known that.
When to Get a Securities Lawyer and What They Will Do for You
If a trade touches undisclosed deal terms, an SEC inquiry, or a tip from someone inside a company, stop and call counsel before doing anything else.
- Preserve everything. Don’t delete emails, texts, or calendar entries, even ones that seem unhelpful.
- Halt related trading. Freeze any transactions connected to the information at issue.
- Build a timeline. A lawyer will reconstruct what you knew and when, which shapes every defense available.
A securities attorney typically runs an internal investigation, manages SEC or DOJ communications, and evaluates whether voluntary disclosure could earn cooperation credit.
Pro Tip: Never alter or delete communications once you suspect a problem. Destroyed evidence, even innocently deleted, can turn a defensible civil matter into an obstruction charge.
Where Enforcement Is Headed, and Why Caution Still Wins
Regulators have sharpened their focus on 10b5-1 plan abuse, executives adopting or amending plans suspiciously close to material events. That scrutiny makes conservative, well-documented compliance more valuable than ever for individual insiders, not just corporations.
If You Need Help: Legal Support for Insider Trading Matters
Murphy’s Law Crypto is a licensed law firm, not an unregulated recovery outfit, built by attorneys who’ve litigated against the SEC and in matters involving Celsius, Terraform Labs, and BitMEX. That courtroom background matters if you’re facing an actual inquiry rather than a hypothetical one.
If your situation involves confidential crypto project information, an undisclosed token launch, or a regulator’s letter that just landed in your inbox, the firm handles internal investigations, SEC and DOJ response strategy, and compliance program drafting for individuals and businesses alike. Confidential intake starts with a straightforward conversation about your facts and your exposure. Reach out for a consultation before you make another move on a trade you’re unsure about.
Primary Sources and Recommended Reading
For deeper reading beyond this guide, these are the authorities counsel will reference directly:
- SEC Rule 10b-5 and Rule 10b5-1: defines the affirmative defense for prearranged trading plans.
- 17 CFR § 240.10b5-1: the exact regulatory text governing plan validity.
- 15 U.S.C. §78u-1: sets the civil penalty formula, up to treble profit or loss avoided.
- Dirks v. SEC analysis: explains the personal-benefit test still used to assess tippee liability today.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- SEC — Insider Trading cases and spotlight
- Investor
- SEC press release on Rule 10b5-1 (2022)
- 17 CFR § 240.10b5-1 (e-CFR / govinfo)
- 15 U.S.C. §78u-1 — Civil penalties for insider trading (U.S. Code)
- Congressional Research Service: Insider trading overview and legislative efforts
FAQ
How difficult is it to prove insider trading?
Proving it requires connecting materiality, nonpublic status, and a breach of duty, often through circumstantial evidence like trading timing and communications rather than direct confessions, which makes cases fact-intensive but far from impossible for the SEC and DOJ to win.
Can I go to jail for insider trading?
Yes. Criminal insider trading is prosecuted by the DOJ and can result in imprisonment plus criminal fines, separate from any civil penalties the SEC imposes.
Is insider trading a felony in the US?
Criminal insider-trading charges are generally prosecuted as federal felonies, carrying potential prison sentences, though the SEC also has the option to pursue the same conduct purely as a civil matter without criminal charges.
Can Congress legally do insider trading?
No. The STOCK Act explicitly confirms that members of Congress and federal employees owe duties of trust regarding material nonpublic information obtained through their official positions, closing any perceived exemption.