
The Securities and Exchange Commission regulates crypto assets that function as investment contracts, while the Commodity Futures Trading Commission regulates digital commodities and the derivatives markets built on them. That division became far clearer in March 2026, when the SEC clarified how federal securities laws apply to crypto assets through a joint interpretation with the CFTC. The interpretation rests on a five-category token taxonomy, the decades-old Howey test for investment contracts, and the Commodity Exchange Act’s definition of a commodity.
If you’re trying to figure out which agency governs your token, exchange, or trading activity, start here:
- Digital commodities (Bitcoin, Ether, and similar decentralized assets): CFTC territory.
- Digital securities and investment contracts: SEC territory, subject to registration and disclosure rules.
- Payment stablecoins: governed primarily by the GENIUS Act, with SEC and CFTC roles limited.
- Digital collectibles and digital tools: generally outside securities and commodities regulation entirely.
Table of Contents
- Why SEC vs CFTC Crypto Jurisdiction Was Unclear for So Long
- What Does the 2026 SEC-CFTC Joint Interpretation Say?
- How Does the Howey Test Apply to Crypto in 2026?
- What Crypto Assets Fall Under CFTC Jurisdiction?
- What Crypto Assets Fall Under SEC Jurisdiction?
- Where Do SEC and CFTC Authority Overlap?
- What Should Crypto Businesses Do Now to Stay Compliant?
- Primary Sources for SEC and CFTC Crypto Rules
- Sources
- FAQ
Why SEC vs CFTC Crypto Jurisdiction Was Unclear for So Long
For most of the last decade, the SEC and CFTC each claimed pieces of the crypto market without a shared rulebook. The SEC leaned on enforcement actions to define the boundaries of a security case by case. The CFTC asserted commodity status over Bitcoin and Ether but had limited authority over spot markets. State regulators added their own licensing regimes on top, and courts issued conflicting rulings on how Howey applied to token sales.
Three developments broke the logjam. The President’s Working Group on Digital Asset Markets released its 2025 report calling for harmonized taxonomy across agencies. That report fed directly into Project Crypto, a joint SEC-CFTC coordination effort that reshaped how the agencies talk to each other. Then, on March 17, 2026, the agencies published their joint interpretation in the Federal Register, effectively ending years of case-by-case guesswork.
That gap in clarity had real costs. Before 2026:
- Exchanges delayed listing decisions because no agency would commit to a classification.
- Startups spent legal budgets on defensive structuring instead of product development.
- Investors had no reliable way to know which agency, if any, would respond to fraud or manipulation.
The 2026 interpretation didn’t eliminate every gray area, but it gave practitioners a shared vocabulary for the first time.
What Does the 2026 SEC-CFTC Joint Interpretation Say?
The interpretation sorts crypto assets into five categories, and where a token lands determines almost everything else: which agency has authority, what registration applies, and what disclosure obligations attach.
- Digital commodities: Decentralized assets like Bitcoin and Ether that don’t depend on a central promoter’s ongoing efforts. Falls under CFTC oversight.
- Digital collectibles: Non-fungible items valued for their uniqueness rather than profit expectation. Generally outside both agencies’ core jurisdiction.
- Digital tools: Tokens that provide network access or utility rather than an investment return. Typically not securities.
- Payment stablecoins: Assets pegged to fiat currency and issued under the GENIUS Act’s permitted-issuer framework.
- Digital securities: Tokens that meet the Howey investment-contract test. Full SEC jurisdiction, including registration and disclosure.
The CFTC’s own press release confirms it will administer the Commodity Exchange Act consistent with the SEC’s interpretation, and it flags that a non-security crypto asset can still meet the CEA’s definition of “commodity.” That overlap is intentional. Chairman Paul Atkins described the shift as moving from an enforcement-first to a clarity-first posture, meaning the agencies now want taxonomy to drive outcomes rather than litigation.
Pro Tip: If you’re classifying a token, read the taxonomy section of the Federal Register posting first, then jump to the “separation indicia” discussion. Those two sections resolve most classification questions without needing outside counsel for a preliminary read.
How Does the Howey Test Apply to Crypto in 2026?
The Howey test still governs whether a crypto asset is a security, and the 2026 interpretation didn’t rewrite it. It applied the same 1946 framework to modern token structures. Under Howey, an investment contract exists when there’s an investment of money, in a common enterprise, with an expectation of profit derived from the efforts of others.
Use this checklist to weigh where a token sits:
- Was money or something of value exchanged for the token? If yes, the first Howey factor is satisfied.
- Do token holders share in a common enterprise? Pooled funds or shared fortunes with a promoter point toward “yes.”
- Do buyers expect profit primarily from the efforts of a promoter or development team? Centralized roadmaps and marketing promises strengthen this factor.
- Has the network achieved genuine decentralization? No single party’s efforts should meaningfully affect the token’s value once this happens.
Indicia pushing toward security status include aggressive marketing promises, a centralized team controlling protocol upgrades, and profit-focused messaging in whitepapers. Indicia supporting non-security status include a functioning decentralized network, real operational utility separate from price speculation, and no ongoing managerial dependency.
This is where the “separation” concept matters. The SEC’s interpretive release explains that a token offered initially as part of an investment contract can later cease to be subject to that contract, once the issuer’s promises are fulfilled and the network no longer depends on centralized efforts. A token sold as a fundraising vehicle in year one can separate from its investment contract in year three if the roadmap milestones are met and control genuinely decentralizes. Howey itself remains binding precedent. This is an application update, not a rewrite of investment contract law.
What Crypto Assets Fall Under CFTC Jurisdiction?
The CFTC has primary authority over digital commodities and the derivatives markets tied to them, plus anti-fraud and anti-manipulation authority in the underlying spot markets. This is the agency’s lane, and it’s a wide one.
- Bitcoin and Ether are treated as digital commodities under the 2026 taxonomy, placing their futures and options contracts squarely under CFTC oversight.
- Designated contract markets (DCMs) handle exchange-traded derivatives on these assets, requiring CFTC registration and ongoing compliance.
- Spot market fraud and manipulation involving a digital commodity can trigger CFTC enforcement even without a derivatives product in play, a point covered in more detail in Risk Disclosure — Scalping-Algo.
Pro Tip: Watch for three signals that a matter will land with the CFTC rather than the SEC: active derivatives trading on the asset, price-manipulation patterns in spot markets, and disputes over DCM registration status. Any one of those tends to point regulators toward Foley Square rather than Chicago’s futures exchanges. For a deeper breakdown of category-specific obligations, see Murphyslawcrypto’s CFTC crypto jurisdiction guide.
What Crypto Assets Fall Under SEC Jurisdiction?
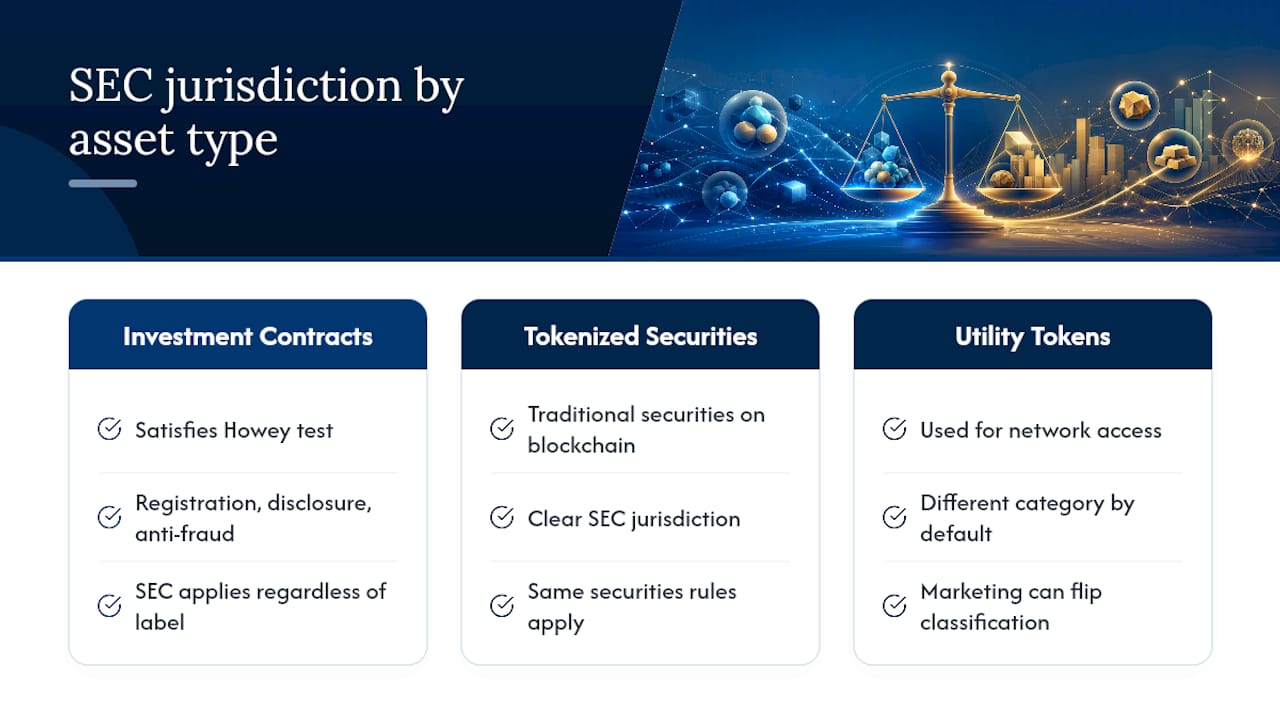
The SEC regulates crypto assets that satisfy the Howey test, along with the registration, disclosure, and anti-fraud obligations that come with security status. If a token behaves like an investment contract, the SEC’s rules apply regardless of what the project calls itself.
Tokenized securities, meaning traditional securities issued on a blockchain, fall under SEC jurisdiction without much debate. A utility token used purely for network access sits in a different category, but marketing choices can flip that classification fast. A whitepaper that promises returns, or a team that keeps promoting price appreciation instead of network function, invites the exact scrutiny detailed in Murphyslawcrypto’s guide to crypto securities law risks.
Pro Tip: Issuers and platforms should treat three items as non-negotiable compliance priorities: securities registration or a valid exemption, custody arrangements that meet SEC expectations, and awareness that secondary-market trading can itself create fresh disclosure obligations even after a token’s initial sale.
Where Do SEC and CFTC Authority Overlap?
Overlap happens most often at the intersection of derivatives and securities, and both agencies retain independent anti-fraud authority regardless of a token’s classification. Since Project Crypto, venue registration has also expanded: SEC-registered national securities exchanges and CFTC-registered designated contract markets can now both facilitate certain spot crypto products, which means the venue you choose shapes which agency has primary oversight.
Two scenarios illustrate the overlap. Market manipulation affecting a digital commodity that also underlies a tokenized derivative can draw both agencies’ attention simultaneously. Similarly, a derivative built on a token still being marketed as an investment opportunity can trigger CFTC review of the derivative and SEC review of the underlying offering.
For exchanges deciding between registration paths:
- Do map your product lineup against the taxonomy before choosing NSE or DCM registration.
- Do document decentralization status for any asset near the security/commodity line.
- Don’t assume one registration covers products in both categories.
- Don’t treat state-level licensing, covered in Murphyslawcrypto’s jurisdiction guide, as a substitute for federal registration.
What Should Crypto Businesses Do Now to Stay Compliant?
Start with classification, then work outward. Run every asset through the five-category taxonomy, map the result to venue and registration requirements, fix any disclosure or custody gaps, and test whether a “separation” event has changed a token’s status since launch.
Watch for these red flags, since any one of them raises enforcement risk substantially:
- Marketing language that promises returns rather than describing utility.
- A development team that retains centralized control years after launch.
- Products that blend investor functions with payment functions in ways that blur stablecoin status.
- Stablecoin issuance without confirmed permitted-issuer status under the GENIUS Act.
Pro Tip: The moment you receive an inquiry letter from either agency, preserve every version of your whitepaper, marketing materials, and internal governance records. Reconstructing a decentralization timeline after the fact is far harder than documenting it as you go. If a civil investigative demand arrives, retain counsel immediately rather than responding informally.
The single most important fact for classifying any crypto asset is this: the 2026 SEC-CFTC joint interpretation ties regulatory authority to a five-category taxonomy, with the Howey test still deciding security status.
| Point | Details |
|---|---|
| Taxonomy drives jurisdiction | Classify assets as digital commodities, collectibles, tools, stablecoins, or securities before assessing compliance needs. |
| CFTC owns commodities and derivatives | Bitcoin, Ether, and their futures/options fall under CFTC oversight and DCM registration rules. |
| SEC owns investment contracts | Tokens meeting the Howey test require securities registration, disclosure, and custody compliance. |
| Separation can change status | A token can exit investment-contract status once issuer promises are fulfilled and control decentralizes. |
| Get counsel before responding to inquiries | Murphyslawcrypto helps businesses classify assets, build compliance programs, and respond to SEC or CFTC investigations. |
Primary Sources for SEC and CFTC Crypto Rules
- SEC press release 2026-30: the SEC’s own summary of the interpretation and taxonomy. Primary source.
- CFTC press release joining the SEC interpretation: confirms CEA administration consistent with the SEC’s approach. Primary source.
- Federal Register posting: the full legal text, including Howey analysis on airdrops, staking, and wrapping. Primary source.
- SEC interpretive release 33-11412: detailed explanation of the separation concept. Primary source.
- The Block’s plain-language summary: useful practitioner commentary, not binding law.
What the 2026 Shift Means Going Forward
Moving from enforcement-first to clarity-first doesn’t finish the job. Businesses still have to translate taxonomy into working compliance playbooks, and litigation risk around partially decentralized protocols hasn’t disappeared. Legislative clarity and judicial review will likely keep shaping this space for years.
Get Legal Counsel Before a Classification Question Becomes an Enforcement Problem
Murphyslawcrypto is the option for crypto businesses that need a classification answer they can actually rely on, not a guess pulled from a blog post. Liam Murphy has litigated cases involving Celsius, Terraform Labs, and BitMEX, which means the firm has already seen how the SEC and CFTC build enforcement cases from the inside.
If your token sits near the security/commodity line, or you’ve received an inquiry letter from either agency, waiting rarely helps your position. Murphyslawcrypto’s crypto compliance consulting team can classify your assets against the 2026 taxonomy and build a defensible compliance record before a regulator asks for one. If an investigation is already underway, start with Murphyslawcrypto’s guide to responding to a regulatory inquiry and reach out for a consultation.
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
Sources
- SEC clarifies the application of federal securities laws to crypto assets
- CFTC joins SEC to clarify the application of federal securities laws to crypto assets
- Application of the Federal Securities Laws to Certain Types of Crypto Assets and Certain Transactions Involving Crypto Assets (Federal Register)
- 33-11412: Application of the Federal Securities Laws to Certain Types of Crypto Assets and Certain Transactions Involving Crypto Assets (SEC interpretive release)
- SEC vs CFTC: Who regulates crypto? (The Block)
FAQ
What Is the Difference Between the CFTC and SEC in Crypto?
The SEC regulates crypto assets that meet the Howey investment-contract test, while the CFTC regulates digital commodities and the derivatives markets built on them, with both agencies retaining independent anti-fraud authority.
Does the SEC Have Jurisdiction Over Crypto?
Yes, but only over assets and transactions that qualify as securities under Howey. The 2026 joint interpretation makes clear that most crypto assets fall outside SEC jurisdiction unless they function as investment contracts.
Is XRP Considered a Security by the SEC?
Classification depends on the specific facts under the Howey test and the 2026 taxonomy, including whether the asset shows genuine decentralization or still depends on centralized managerial efforts; there is no single blanket answer that applies to every XRP transaction.
Is Coinbase Regulated by the CFTC?
Coinbase’s spot crypto trading falls partly under CFTC anti-fraud and anti-manipulation authority as a venue trading digital commodities, while any securities-classified products it lists would trigger SEC oversight instead.
Who Regulates Cryptocurrency in the United States Overall?
No single agency regulates all cryptocurrency. The SEC, CFTC, and IRS each have distinct roles, covering securities, commodities and derivatives, and tax treatment, respectively, with state regulators adding another compliance layer.