
SEC cooperation credit is a discretionary benefit the Securities and Exchange Commission may award to an individual or company that provides substantial assistance during an enforcement investigation. It is not a formula, and it is never owed to anyone as a matter of right. When the SEC grants it, the practical results can include reduced charges, lower civil penalties, a decision to forgo enforcement action entirely, or a deferred prosecution agreement (DPA) or non-prosecution agreement (NPA) that resolves the matter without a formal case.
The SEC’s Division of Enforcement governs how credit gets evaluated, and the Commission’s own policy statement on cooperation sets the analytical framework staff use. Understanding that framework, rather than guessing at it, is what separates a cooperation strategy that works from one that backfires.
Here is what cooperation credit typically produces when the SEC decides to grant it:
- Declining to bring an enforcement action at all
- Narrowing the charges filed against an individual or entity
- Reducing or waiving civil monetary penalties
- Deferring the penalty question until cooperation is substantially complete
- Entering into a DPA or NPA instead of litigating
- Softening mitigation language in the final order, which can affect collateral consequences like industry bars
Statistic Callout: The SEC’s own retrospective on its cooperation program notes that in a meaningful share of resolved cooperation matters, individuals who cooperated ultimately paid no civil penalty at all, with the penalty question deferred and then dropped once cooperation was verified as complete and truthful.
Key Takeaways
SEC cooperation credit rewards timely, truthful, substantive assistance, evaluated under a discretionary four-factor framework, and it can reduce or eliminate charges but never guarantees an outcome.
| Point | Details |
|---|---|
| Credit is discretionary | The SEC weighs assistance, the matter’s importance, accountability interest, and the cooperator’s profile case by case. |
| Timing beats volume | Being first to report and offering substantive help early often matters more than the sheer amount of documents produced. |
| Outcomes span a wide range | Results can include declined charges, reduced penalties, bifurcated settlements, or a DPA/NPA instead of litigation. |
| Shielding executives backfires | Protecting senior officials while claiming cooperation is one of the most damaging strategic mistakes a company can make. |
| Early counsel shapes the outcome | Murphy’s Law Crypto helps compliance teams scope internal investigations and remediation before bulk production begins. |
Table of Contents
- What Is SEC Cooperation and Why Does the Program Exist?
- What Counts as Substantial Assistance to the SEC?
- How Does the SEC Decide Who Gets Cooperation Credit?
- What Outcomes Can the SEC Actually Grant for Cooperation?
- What Should Compliance Officers Do to Cooperate Effectively?
- How Does SEC Cooperation Affect Parallel Criminal Investigations?
- What Are the Limits of SEC Cooperation Credit?
- Which SEC Authorities and Speeches Define Cooperation Credit?
- What Does the SEC Cooperation Process Typically Look Like?
- Why Early Counsel and Real Remediation Change the Calculus
- How Murphy’s Law Crypto Helps With Cooperation Strategy and Regulatory Defense
- Primary Sources and Further Reading
- Sources
- FAQ
What Is SEC Cooperation and Why Does the Program Exist?
The SEC created its formal cooperation framework because enforcement staff cannot investigate complex securities and crypto fraud cases efficiently without inside help. Document reviews, forensic accounting, and third-party subpoenas take time and money that voluntary cooperation can cut dramatically. A company that hands over the results of its own internal investigation, complete with witness interview summaries and a map of who knew what and when, can save the agency months of work.
That efficiency argument is only half the story. The Commission’s policy statement frames cooperation as a tool for protecting investors, not just a courtesy to defendants. Faster, more accurate investigations mean faster relief for harmed investors and quicker identification of ongoing misconduct that might otherwise continue undetected.
Credit is evaluated case by case, and the Division of Enforcement has real discretion over how much weight to give any single act of cooperation. Two companies that each turn over similar volumes of documents can end up with very different outcomes depending on timing, candor, and how the SEC views the underlying misconduct. That variability frustrates a lot of compliance officers who want a checklist that guarantees results. There isn’t one. What exists instead is a framework, and it rewards people who understand it well before they act.
What Counts as Substantial Assistance to the SEC?
Cooperation credit covers a wider range of conduct than most people assume, and it is worth knowing the menu before deciding what to offer. The SEC’s Enforcement Manual describes several formal tools staff can use to reward assistance, and the informal categories of help matter just as much as the formal agreements.
Substantial assistance can take several forms:
- Producing documents voluntarily and ahead of a formal request, especially when a party flags the records that matter most
- Making witnesses available for interviews and facilitating access to former employees who might otherwise be reluctant to talk
- Translating foreign-language materials or explaining unfamiliar recordkeeping and trading systems
- Conducting an internal investigation and sharing its findings, including interview notes and root-cause analysis
- Identifying additional witnesses or wrongdoers the SEC had not yet located
- Waiving certain procedural protections to speed the pace of the inquiry
The benefits that can follow are equally varied. On the lenient end, the SEC may issue a formal declination, meaning no enforcement action follows at all. In the middle range, the agency might narrow the charges, agree to a bifurcated penalty proceeding where the amount is decided later, or resolve the matter through a DPA or NPA rather than litigation, tools the Enforcement Manual explicitly authorizes staff to use.
It helps to separate informal cooperation from formal agreements early. Informal cooperation, voluntarily producing documents, making witnesses available, sharing internal findings, preserves flexibility and creates no binding obligations. A formal cooperation agreement or DPA locks in specific undertakings, reporting requirements, and deadlines. Neither path guarantees credit, but each carries a different risk profile, and choosing between them is a strategic decision that deserves counsel’s input before any commitment gets made.
How Does the SEC Decide Who Gets Cooperation Credit?
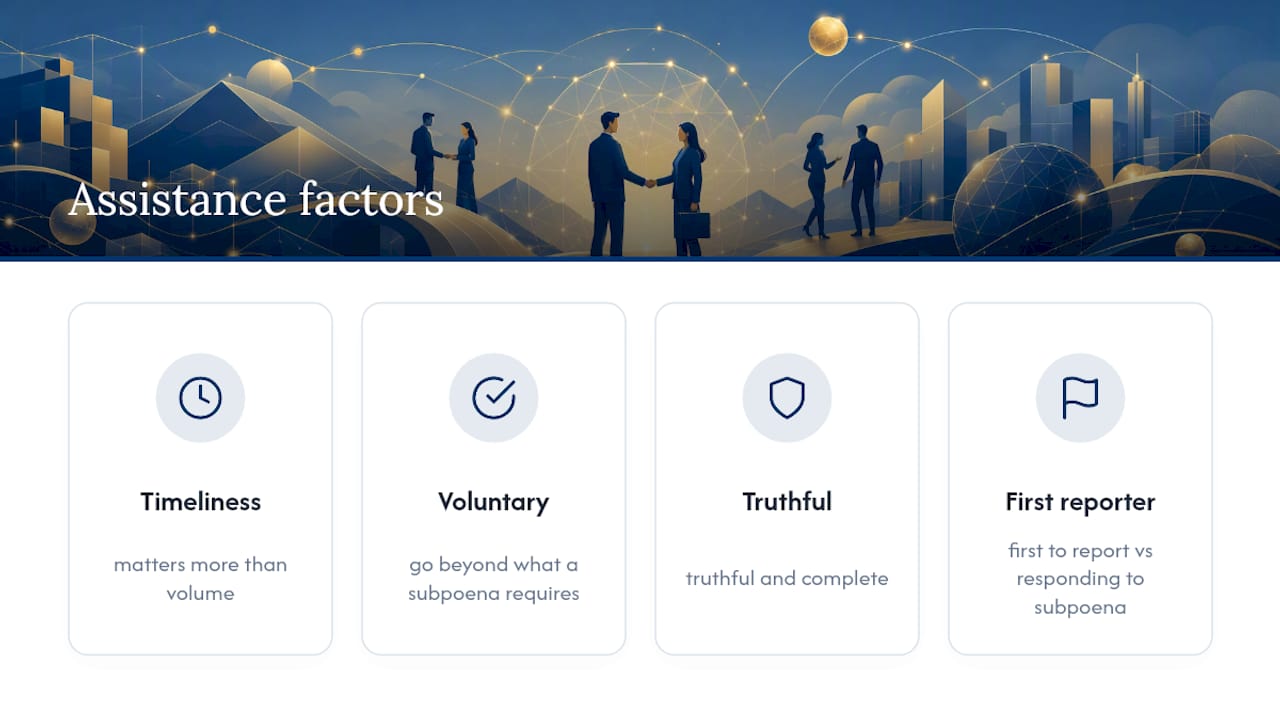
The Commission’s cooperation policy statement, codified at 17 CFR § 202.12, lays out four considerations staff weigh when deciding how much credit to give. None of them operates in isolation, and the SEC treats the analysis as fact-specific rather than mechanical.
The assistance provided. Staff look at the timeliness of the cooperation, whether it was voluntary, whether it was truthful and complete, and whether the cooperator was the first to report the conduct or merely responded to a subpoena that was already coming.
The importance of the matter. This considers the seriousness of the securities law violation, the amount of harm to investors, and the number of victims affected. A minor recordkeeping lapse and a scheme that drained millions from retail investors sit at very different points on this scale.
The interest in holding the individual accountable. Here the SEC weighs the person’s role in the misconduct, their degree of scienter, whether they profited from it, and whether their conduct was isolated or part of a broader pattern.
The profile of the cooperator. This looks at the individual’s or entity’s history, including prior violations, their overall conduct during the investigation, and any compliance and remediation record that speaks to future risk.
A former SEC Enforcement Director’s remarks framed the standard plainly: effective cooperation means going beyond what a subpoena requires. Self-policing, early self-reporting, real remediation, and genuine collaboration with staff are what separate credit-worthy conduct from mere compliance with a legal obligation to respond.
None of these four factors carries a fixed weight, and the SEC has never published a scoring rubric because one doesn’t exist. Timeliness tends to matter more than volume. A company that calls the SEC before the agency even knows there’s a problem starts from a stronger position than one that cooperates only after receiving a subpoena, even if the second company eventually produces more documents.
What Outcomes Can the SEC Actually Grant for Cooperation?
The benefits of cooperation credit run on a spectrum, and where a case lands on that spectrum depends heavily on how the four-factor analysis shakes out. The SEC’s own Division of Enforcement page on cooperation benefits lists the following outcomes, roughly ordered from most to least favorable:
- Declining to bring an enforcement action. The SEC decides, after reviewing the cooperator’s substantial assistance and the overall equities, that no case is warranted.
- Narrowing the charges. Instead of charging fraud, the agency might charge a lesser violation, or drop charges against certain individuals while proceeding against others.
- Reducing or waiving civil penalties. The company or individual still settles, but the monetary sanction reflects a discount for the value of the cooperation provided.
- Bifurcating the penalty determination. The SEC settles liability first and leaves the penalty amount open, often pending completion of ongoing cooperation obligations.
- Entering into a DPA or NPA. The matter resolves through a negotiated agreement rather than a litigated or settled enforcement action, frequently with compliance undertakings attached.
- Softening remedial sanctions. Industry bars, suspensions, or officer-and-director prohibitions may be shortened or avoided where cooperation and remediation support a lesser sanction.
Outcomes diverge sharply between individuals and entities. For an individual, cooperation credit often shows up in the form of testimony that avoids an industry bar or a reduced personal penalty, since the person’s own conduct and truthfulness are what’s being evaluated. For a company, credit tends to hinge on corporate undertakings: fixing the compliance program, disgorging ill-gotten gains, and following through on remediation commitments the SEC will monitor.
A retrospective from SEC enforcement staff describes bifurcated settlements as a recurring pattern in cooperation matters. Liability gets resolved on a known timeline, but the penalty amount stays open until the agency can confirm that promised cooperation, additional testimony, ongoing document access, actually materialized. That structure gives the SEC leverage to make sure cooperation commitments get honored rather than abandoned once liability is locked in.
What Should Compliance Officers Do to Cooperate Effectively?
The single biggest mistake companies make is waiting to decide on a cooperation strategy until after the SEC has already issued a subpoena. By then, some of the credit for being first to report is already gone. A workable sequence looks like this:
Preserve everything immediately. The moment potential misconduct surfaces, a litigation hold needs to go out covering emails, chat logs, trading records, and any relevant blockchain transaction data if the matter involves crypto assets.
Run a targeted internal investigation, not a fishing expedition. Scope the review around the specific conduct at issue rather than launching an open-ended audit that takes months and produces more privileged material than useful findings.
Decide on self-reporting with counsel, not compliance alone. Whether and when to approach SEC staff voluntarily is a legal judgment with real consequences, and it should be made jointly by outside counsel and senior compliance leadership, not by compliance in isolation.
Remediate before you’re asked to. Discipline the people responsible, fix the control gap that allowed the conduct, and where investors were harmed, take steps toward repayment. SEC officials have repeatedly said that meaningful, timely remediation strengthens a cooperation case more than almost anything else a company can offer.
Prepare witnesses honestly. Coach witnesses on process and clarity, never on substance. Staff can tell the difference, and coaching that shapes testimony rather than clarifies it destroys credibility fast.
Privilege is where a lot of well-intentioned cooperation plans go sideways. Sharing the results of an internal investigation, findings, conclusions, remedial recommendations, does not necessarily waive privilege over the underlying interview memos and legal analysis, if it’s handled correctly. Sharing the memos themselves usually does. Outside counsel should control what gets shared and in what form, because a careless waiver in one matter can expose privileged material in unrelated civil litigation down the line.
Who leads matters too. Outside counsel experienced in SEC enforcement should generally drive the strategy and the direct dialogue with staff, while internal counsel manages the company-side logistics: document collection, employee coordination, and board reporting. Blurring those roles creates confusion about who is actually speaking for the company when SEC staff calls.
Pro Tip: Enforcement staff have said publicly that early conversations about how your document systems are organized and who the key witnesses are can matter more than the volume of records you eventually produce. Offer to walk staff through your email retention architecture and flag your “hot” documents before they even ask. That kind of substantive transparency, described in remarks from SEC enforcement leadership, tends to register as real cooperation rather than a document dump designed to bury the ball.
How Does SEC Cooperation Affect Parallel Criminal Investigations?
Civil SEC enforcement and criminal prosecution by the Department of Justice run on different tracks, but a securities fraud matter, especially one involving crypto assets, frequently triggers both at once. The SEC seeks civil remedies: disgorgement, penalties, injunctions, and industry bars. The DOJ seeks criminal remedies: fines and imprisonment. Cooperation with one agency can shape the outcome with the other, for better or worse.
A statement made to SEC staff can end up in a criminal prosecutor’s file, and testimony given in an SEC deposition can be used against the same person in a parallel criminal case. That reality creates genuine tension for individuals asked to cooperate, particularly where Fifth Amendment concerns are live.
- Notify counsel handling any parallel criminal exposure before agreeing to any SEC interview or testimony
- Assume that anything said to SEC staff may be shared with or discoverable by DOJ prosecutors
- Coordinate messaging across both civil and criminal counsel so that statements made to one agency don’t create admissions that damage the other proceeding
- Understand that a formal DPA or NPA with the DOJ carries different terms, undertakings, and monitoring obligations than an SEC settlement, and the two need to be negotiated with awareness of each other
- Never assume cooperation with the SEC buys leniency from the DOJ automatically. The agencies coordinate but decide independently
Synchronized counsel strategy is not optional when both agencies are circling the same conduct. A remediation statement or an admission made to satisfy SEC staff can become the centerpiece of a DOJ indictment if it isn’t carefully worded. Anyone facing this dual exposure should treat the distinction between civil and criminal crypto fraud exposure as a starting point for strategy, not an afterthought.
What Are the Limits of SEC Cooperation Credit?
Cooperation credit is discretionary, and the SEC balances it against the public interest in every case. That balancing act means a party can do everything right and still not receive the credit it hoped for, particularly where the underlying misconduct was severe or the harm to investors was extensive. 17 CFR § 202.12 makes clear that accountability concerns can outweigh cooperation, even substantial cooperation, when the conduct at issue is serious enough.
Several recurring mistakes undermine cooperation credit before it ever gets awarded:
Shielding senior executives. Attempting to cooperate while protecting the people most responsible for the misconduct is widely regarded by SEC staff as the single most damaging strategic error a company can make. Enforcement retrospectives describe this pattern as something staff watch for specifically, and it tends to erase whatever goodwill genuine cooperation elsewhere in the case might have built.
Delay. Waiting until a subpoena arrives, or worse, until a whistleblower tip becomes public, forfeits most of the credit available for being first to report.
Inconsistent statements. Testimony or document productions that contradict earlier representations damage credibility with staff and can turn a cooperator into a target.
Failing to remediate. Promising to fix a control gap and then not following through is one of the fastest ways to lose credit that was tentatively extended earlier in the process.
Gamesmanship in production. Burying relevant documents in massive, unindexed productions, rather than flagging what matters, reads as obstruction dressed up as compliance.
Cooperation also doesn’t erase collateral consequences. A reduced SEC penalty doesn’t prevent a parallel civil class action from investors, and it doesn’t automatically shield an individual from an industry bar sought by a self-regulatory organization. Cooperation can soften these outcomes. It rarely eliminates them entirely, and anyone counting on cooperation credit to make a problem disappear is planning around a misunderstanding of what the program actually does.
Which SEC Authorities and Speeches Define Cooperation Credit?
Anyone building a cooperation strategy should read the primary sources directly rather than relying on secondhand summaries, because the SEC’s own language often reveals nuance that commentary strips out.
| Source | Type | Why it matters |
|---|---|---|
| Benefits of Cooperation With the Division of Enforcement | Policy page | Lists the concrete outcomes staff can recommend and gives real examples of credit awarded |
| Policy Statement / 17 CFR § 202.12 | Regulation | Codifies the four-factor framework that governs every cooperation analysis |
| SEC Enforcement Manual | Internal guidance | Describes formal tools like cooperation agreements, DPAs, NPAs, and the Cooperation Committee |
| Remarks at Securities Enforcement Forum West | Speech | Sets out staff expectations for what counts as substantive, above-and-beyond cooperation |
| The SEC’s Cooperation Program: Reflections on Five Years | Retrospective speech | Documents real patterns in outcomes, including bifurcated penalties and zero-penalty resolutions |
The Division of Enforcement’s benefits page cites actual orders where staff recommended credit for full and truthful cooperation, giving readers a sense of what “substantial assistance” looks like in practice rather than in the abstract. The five-year retrospective is particularly useful because it was written after the program had enough of a track record to identify patterns, rather than just describing the policy’s original intent.
One insight worth internalizing: cooperating with the SEC’s investigatory process does not require agreeing with its legal conclusions. A former Enforcement Director made this point explicitly, noting that a party can be a fully cooperative source of facts while still contesting liability zealously once charges are filed. Cooperation and advocacy on the merits are not mutually exclusive.
What Does the SEC Cooperation Process Typically Look Like?
Cooperation unfolds in stages, and understanding the sequence helps compliance officers budget time and resources realistically rather than assuming the process moves faster than it does.
| Stage | What the SEC typically expects |
|---|---|
| Preservation and initial contact | A litigation hold in place immediately, followed by early outreach to staff if self-reporting |
| Internal review | A scoped internal investigation with findings the company is willing to share, not just a compliance memo |
| Document production | Voluntary production ahead of formal requests, with hot documents flagged rather than buried in volume |
| Witness interviews | Access to current and former employees, coordinated through counsel rather than left to chance |
| Settlement and penalty phase | Continued cooperation through the negotiation, sometimes with the penalty amount left open pending final verification |
Timelines vary enormously depending on complexity. A single-entity matter with domestic witnesses and clean documentation can move through initial cooperation stages in a matter of months. A cross-border case involving overseas witnesses, foreign-language document translation, or a parallel DOJ criminal investigation can stretch the same process well past a year, sometimes several. Crypto matters frequently fall into the harder category, since blockchain forensic work and offshore exchange records add technical and jurisdictional complexity that a traditional securities case doesn’t carry.
Why Early Counsel and Real Remediation Change the Calculus
The conventional wisdom on cooperation credit treats it like a negotiating chip: cooperate enough, and the SEC will reward it proportionally. That framing undersells what actually drives outcomes. The four-factor test rewards sincerity and timing more than volume, and sincerity is nearly impossible to manufacture after the fact. A company that waits until it’s caught to start acting cooperative is trying to fake a posture that only works when it’s genuine from the start.
The most consistent theme across SEC speeches and policy on this topic is that staff can tell the difference between a company managing its exposure and a company actually trying to fix a problem. That distinction shows up in small tells: whether a company flags its own bad documents, whether remediation happens before or after it’s demanded, whether senior executives face real consequences or get quietly reassigned. None of that is hard to detect once you’ve reviewed enough cooperation cases, and SEC staff have reviewed a lot of them.
My recommendation for compliance officers who suspect misconduct has occurred is blunt: run a targeted internal investigation and build a remediation plan before you produce a single document in bulk. Bulk production without context or narrative rarely earns credit, no matter how complete it is. A scoped investigation that identifies the problem, fixes the control gap, and disciplines the people responsible gives you something to actually bring to the table when you talk to staff. Firms with experience litigating crypto enforcement matters, including cases involving exchanges and token issuers facing SEC scrutiny, tend to build that sequencing into the earliest stage of engagement rather than treating it as an afterthought once a subpoena lands.
How Murphy’s Law Crypto Helps With Cooperation Strategy and Regulatory Defense
Murphy’s Law Crypto is a licensed crypto law firm built specifically for the moment your compliance team realizes an SEC inquiry might be coming, or already has. Unlike generalist firms bolting crypto onto a securities practice, our attorneys have litigated matters involving Celsius, Terraform Labs, and BitMEX, which means we understand how the SEC’s cooperation framework actually plays out in digital asset cases, not just traditional securities ones.
Our team helps with the exact decisions this article covers: scoping a targeted internal investigation before any document leaves the building, deciding whether self-reporting makes sense given your specific facts, coordinating with parallel DOJ criminal exposure when both agencies are circling the same conduct, and designing remediation that actually holds up under SEC scrutiny rather than looking good on paper. If you’ve received a civil investigative demand or a subpoena, the window to shape your cooperation posture is narrower than most compliance teams assume, and it closes fast once staff has formed an early impression of your candor.
This article is general information, not legal advice specific to your situation. If your company or you personally are facing an SEC inquiry, contact Murphy’s Law Crypto for a strategy consultation before you decide what to produce, what to say, or who should say it.
Primary Sources and Further Reading
- Benefits of Cooperation With the Division of Enforcement — the SEC’s own outline of what cooperation credit can produce, with real examples of credit granted.
- Policy Statement Concerning Cooperation by Individuals in its Investigations and Related Enforcement Actions — the regulatory text setting out the four-factor analytical framework.
- 17 CFR § 202.12 — the codified version of the cooperation policy statement.
- SEC Enforcement Manual — internal guidance describing cooperation agreements, DPAs, NPAs, and the Cooperation Committee.
- Remarks at Securities Enforcement Forum West — a former Enforcement Director’s account of what effective cooperation looks like in practice.
- The SEC’s Cooperation Program: Reflections on Five Years of Experience — a retrospective covering real patterns in penalty outcomes and common mistakes.
- SEC Division of Enforcement: What It Is and What It Does — background on the office that evaluates every cooperation request.
Sources
- Benefits of Cooperation With the Division of Enforcement
- Policy Statement Concerning Cooperation by Individuals in its Investigations and Related Enforcement Actions
- Remarks at Securities Enforcement Forum West (Gurbir Grewal)
- SEC Enforcement Manual (Division of Enforcement)
- 17 CFR § 202.12 – Policy statement concerning cooperation by individuals
FAQ
What Is SEC Cooperation Credit?
SEC cooperation credit is a discretionary benefit the agency may award to a person or company that provides substantial, timely, and truthful assistance during an enforcement investigation, potentially leading to reduced charges, lower penalties, or no action at all.
What Are the Most Common SEC Violations Tied to Cooperation Cases?
Cooperation credit comes up most often in cases involving securities fraud, disclosure violations, insider trading, and, increasingly, unregistered crypto securities offerings and market manipulation involving digital assets.
Does the SEC Investigate Crypto Cases?
Yes. The SEC actively investigates crypto-related securities violations, including unregistered offerings, fraud, and market manipulation involving digital assets, and cooperation credit principles apply to those matters the same way they apply to traditional securities cases.
How Is Cooperation Credit Different for Individuals Versus Companies?
Individuals typically earn credit through truthful testimony and personal assistance that can reduce penalties or avoid industry bars, while companies earn it through internal investigations, document production, and remediation commitments the SEC can verify over time.
Can Cooperation With the SEC Affect a Parallel Criminal Case?
Yes. Statements made to SEC staff can be shared with or used by DOJ prosecutors in a parallel criminal matter, which is why coordinating civil and criminal counsel before any cooperation begins is critical.