
A crypto asset investment contract is any transaction in which a buyer invests money in a common enterprise and reasonably expects profits from the managerial efforts of others — a definition the U.S. Supreme Court established in SEC v. W.J. Howey Co. and that the SEC enforces as the primary federal regulator of digital-asset offerings. The document’s label, whether a SAFT, a Token Purchase Agreement, or a plain sale receipt, does not determine the legal outcome. Economic reality does. The SEC’s 2026 interpretive guidance makes clear that even a non-security crypto asset can be offered and sold subject to an investment contract, and the DAO Report established as early as 2017 that token sales can trigger full federal securities obligations. If a platform fails or an issuer disappears, Securities Investor Protection Act (SIPA) coverage may not apply, which means investor protections can differ sharply from those available in traditional securities accounts.
Key Takeaways
A crypto asset investment contract is defined by economic reality under the Howey test, not by the document’s label, and unregistered offerings expose investors to significant legal risk with limited statutory protections.
| Point | Details |
|---|---|
| Howey test controls | Four elements determine investment-contract status: money invested, common enterprise, profit expectation, reliance on others’ efforts. |
| Labels are irrelevant | A SAFT, Token Purchase Agreement, or sale receipt does not determine securities status; the offer’s economic reality does. |
| Separation can occur | A non-security token can shed investment-contract status once the network is genuinely decentralized and issuer efforts are no longer material. |
| Top red flags | Discounted pre-sale pricing, issuer-controlled development, resale restrictions, and profit promises are the strongest warning signs. |
| Murphyslawcrypto | Murphy’s Law handles fraud recovery litigation, forensic tracing, and regulatory defense for investors who suspect they bought an unregistered investment contract. |
Table of Contents
- How does U.S. law define a crypto asset investment contract?
- When does a non-security token become subject to an investment contract?
- What agreement types and clauses signal an investment contract?
- How can you spot red flags before you invest?
- What are the consequences if an offering qualifies as an investment contract?
- What should you do if you already bought a suspected investment contract?
- Common scams that exploit crypto investment contract structures
- What investor protections apply under U.S. law?
- Why document review and early counsel are the difference-makers
- Murphy’s Law handles the legal complexity so you can focus on recovery
- Sources
- FAQ
How does U.S. law define a crypto asset investment contract?
The Howey test is the controlling framework. Courts and the SEC apply four elements to every offering:
- Investment of money — the buyer transfers value, including crypto, fiat, or other consideration.
- Common enterprise — the buyer’s fortunes are tied to the issuer or a pool of other investors.
- Reasonable expectation of profits — marketing or contract language leads the buyer to expect a financial return.
- Efforts of others — those profits depend predominantly on the issuer’s or a third party’s managerial work, not the buyer’s own efforts.
The SEC’s 2026 interpretive guidance applies this framework directly to crypto assets and clarifies that a non-security token can still be the subject of an investment contract when the surrounding offer and sale satisfy Howey. The guidance supersedes the 2019 Framework but builds on the same analytical structure.
Courts have consistently reinforced this point. Labels are irrelevant; what matters is whether the transaction induced reliance on issuer efforts to generate a return.
When does a non-security token become subject to an investment contract?
A token that functions as a utility asset in one context can become subject to an investment contract in another, depending entirely on how it is offered and sold. Issuer representations — promises about future development, price appreciation, or platform growth — can attach investment-contract status to an otherwise non-security asset.
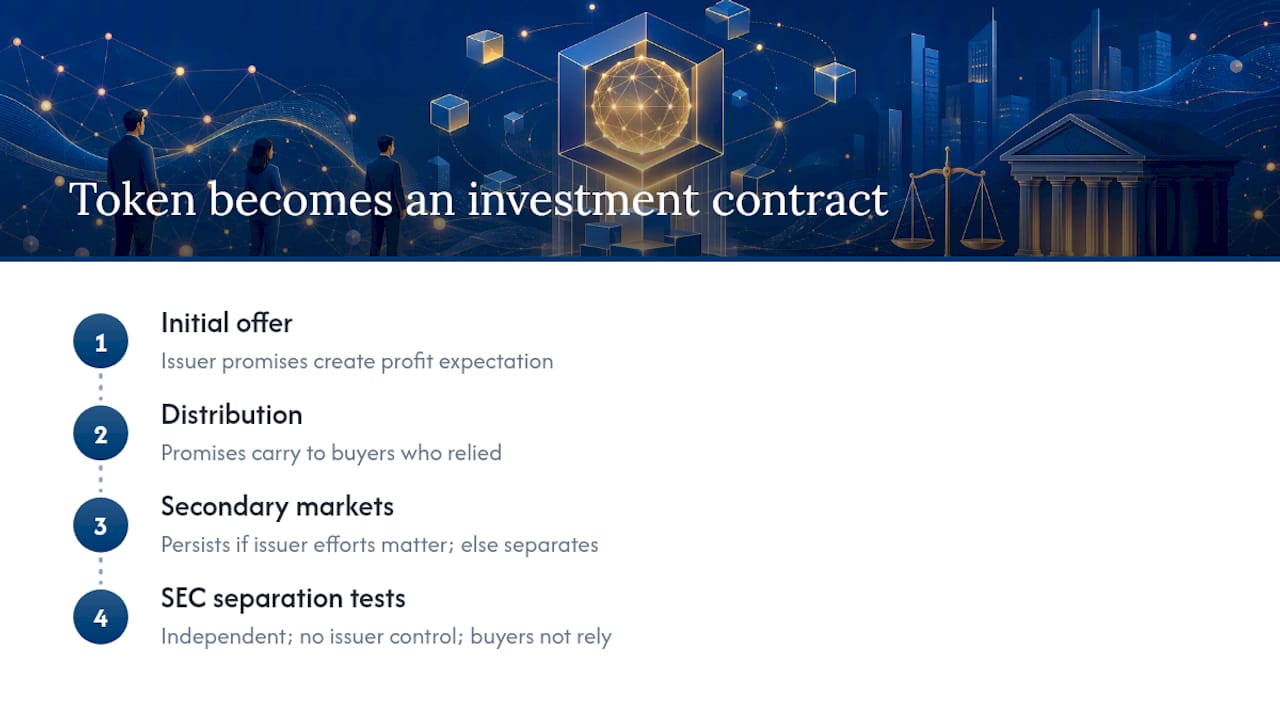
The lifecycle matters. At the initial offer stage, issuer promises in a whitepaper or token sale agreement create the expectation of profit. During distribution, those promises carry to buyers who relied on them. In secondary markets, the investment contract can persist if the issuer’s managerial efforts still drive value, or it can “separate” from the asset once the network becomes genuinely decentralized and no single party’s efforts are material to the token’s value.
The SEC’s 2026 guidance sets specific factors for when separation occurs: the asset must function independently of the issuer, the issuer must no longer control development or governance, and buyers in the secondary market must not reasonably rely on the issuer’s continued efforts. Until those conditions are met, subsequent purchasers may still be buying into an investment contract even when they have no direct relationship with the original issuer.
What agreement types and clauses signal an investment contract?
Investors encounter several document types in crypto transactions. Understanding what each one is, and what to look for inside it, is practical due diligence.
- SAFT (Simple Agreement for Future Tokens): A pre-sale instrument promising token delivery upon network launch; almost always structured as a security.
- Token Purchase Agreement: A direct sale of tokens, often with representations about the project’s development roadmap.
- Digital Asset Purchase and Sale Agreement: Spot-market sale of existing tokens; can be commercial or investment-oriented depending on issuer representations.
- Exchange/Platform User Agreement: Governs trading and custody on a platform; typically a commercial contract, but bundled issuer representations can shift the analysis.
Within any of these documents, the following clauses indicate an investment orientation:
- Promises of price appreciation or yield
- Issuer-controlled development milestones tied to token value
- Discounted pricing for early buyers relative to anticipated public market price
- Resale facilitation or secondary-market listing commitments
- Buyback or redemption features tied to issuer performance
- Restrictions on token use that preserve scarcity for investment purposes
The StoneX Digital Asset Trading Agreement filed with the SEC illustrates commercial trading terms: trade confirmations, settlement mechanics, and counterparty responsibility clauses that characterize a spot transaction rather than an issuer-led investment. The Gemini/NuStar Digital Asset Purchase and Sale Agreement similarly shows purchaser sophistication acknowledgements and risk disclosures that are standard in arm’s-length commercial sales. Neither document contains issuer promises about future value, which is precisely what distinguishes a commercial sale from an investment contract.
Pro Tip: Check the project’s whitepaper and social media alongside the formal agreement. Promotional materials that promise returns or describe the issuer’s roadmap as the driver of token value are often the decisive evidence in enforcement actions, even when the contract itself is carefully worded to avoid securities language.
How can you spot red flags before you invest?
Ask the issuer these questions directly before committing capital.
Who controls the project’s development, and is that team publicly identified? A project where a single team controls protocol upgrades, treasury funds, and governance votes satisfies the “efforts of others” prong almost automatically.
Are tokens sold at a discount to anticipated market price? Discounted pre-sale pricing is a strong indicator that buyers are purchasing an investment expectation, not a utility.
Are there resale restrictions or lock-up periods? Restrictions that expire once a secondary market develops suggest the issuer knows the initial sale is investment-oriented.
Beyond those questions, verify on-chain and off-chain claims independently. Use a block explorer such as Etherscan to confirm token supply, holder concentration, and contract ownership. Check GitHub for genuine development activity rather than a dormant repository. Confirm that leadership credentials are verifiable on LinkedIn or through professional licensing databases. If the project claims audited financials or a security audit, locate the actual audit report from the named firm, not a summary on the project’s own website.
What are the consequences if an offering qualifies as an investment contract?
The stakes are significant for both investors and issuers. FINRA’s investor guidance notes that classification as a security or commodity turns on offer-and-sale facts, and that crypto offerings often lack the disclosures investors receive in registered securities transactions.
Key consequences include:
- SEC enforcement: Unregistered securities offerings can trigger stop orders, disgorgement demands, civil penalties, and injunctions.
- Registration requirements: Issuers must register the offering or qualify for an exemption; failure exposes them to rescission claims from every buyer.
- Rescission rights: Investors who bought an unregistered security may have a statutory right to recover their purchase price plus interest.
- Freeze orders: Courts can freeze issuer assets pending enforcement, which can trap investor funds for years.
- Liquidity impact: Tokens subject to unregistered securities status cannot legally trade on most U.S. platforms without registration.
| Consequence | Investor implication |
|---|---|
| SEC enforcement action | Trading halted; recovery tied to enforcement timeline |
| Registration failure | Statutory rescission right; issuer liable for purchase price plus interest |
| Asset freeze order | Funds inaccessible during litigation, often 12 months |
| SIPA non-applicability | No SIPC backstop; recovery depends on civil litigation or bankruptcy |
On crypto custody, SIPA protection generally does not extend to crypto assets held at unregistered custodians. If the platform holding your tokens is not a registered broker-dealer subject to SIPA, your assets are unsecured claims in bankruptcy, not protected customer property.
What should you do if you already bought a suspected investment contract?
Act quickly. Evidence degrades, issuers disappear, and statutes of limitations run.
- Preserve all promotional materials. Download the whitepaper, save screenshots of the project website, and archive any emails or social media posts in which the issuer made promises about returns or development.
- Download transaction receipts. Export your full transaction history from the exchange or wallet, including timestamps, amounts, and wallet addresses.
- Capture account screenshots. Document your current balance, any locked or restricted positions, and any communications from the platform.
- Preserve wallet metadata. If you hold tokens in a self-custody wallet, record the wallet address, creation date, and any on-chain interactions with the issuer’s contracts.
- File an SEC tip. Submit through the SEC’s Tips, Complaints, and Referrals portal. State regulators and the FBI’s Internet Crime Complaint Center (IC3) are additional reporting channels.
- Contact qualified legal counsel before taking further action. An attorney can advise on civil rescission claims, fraud causes of action, and whether a class action is viable. Counsel will ask for the materials listed in steps 1 through 4, so gathering them first accelerates the intake process.
Early legal counsel materially improves recovery odds because it preserves the evidentiary record before issuers can delete or obscure it.
Common scams that exploit crypto investment contract structures
Fraudulent schemes frequently exploit the investment-contract framework by mimicking legitimate token sales.
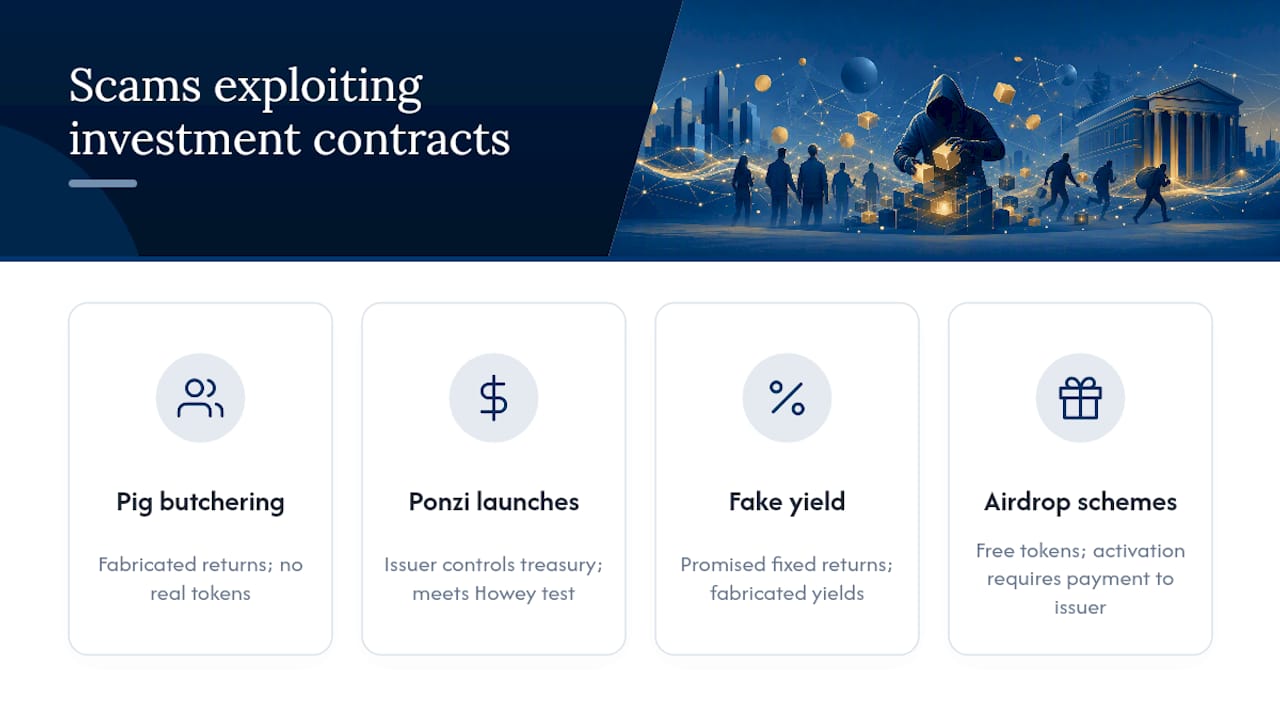
Pig butchering scams build trust over weeks through social engineering, then direct victims to fraudulent platforms that display fabricated returns. The “investment contract” is entirely fictitious; no tokens exist.
Ponzi-structured token launches pay early investors with later investors’ capital while the issuer controls the treasury. Projects like these satisfy every Howey prong and have generated some of the largest SEC enforcement actions in the digital-asset space, including matters involving Terraform Labs.
Fake yield platforms promise fixed annual returns on deposited crypto, structuring the arrangement as a “staking agreement” or “liquidity provision contract.” The issuer’s managerial control over the yield mechanism makes these classic investment contracts, and the promised returns are often fabricated.
Airdrop-to-invest schemes distribute free tokens to create a holder base, then pressure recipients to “activate” their tokens by sending additional crypto to an issuer-controlled address. The activation payment is the investment; the promised appreciation is the profit expectation.
What investor protections apply under U.S. law?
When a crypto offering qualifies as a security, investors gain access to the full suite of federal securities protections. Section 12(a)(1) of the Securities Act of 1933 gives buyers of unregistered securities a rescission right: they can demand their money back plus statutory interest. Section 10(b) of the Securities Exchange Act of 1934 and SEC Rule 10b-5 provide fraud claims when issuers make material misstatements or omissions.
State blue-sky laws add a parallel layer. Most states have their own securities registration requirements, and violations can support state-level enforcement and private claims independent of federal action.
Where protections are limited: SIPA covers customer property at registered broker-dealers, and most crypto platforms are not registered broker-dealers. Crypto assets held at unregistered platforms are generally not SIPA-protected, meaning investors in platform insolvencies become unsecured creditors. The Celsius and Voyager bankruptcies illustrated this gap clearly.
This article provides general legal information, not legal advice. Consult a qualified attorney for guidance specific to your situation and verify current rules with the SEC or relevant regulators.
Why document review and early counsel are the difference-makers
The cases that resolve favorably share one characteristic: the investor preserved evidence before the issuer could destroy it. In matters involving Celsius, Terraform Labs, and BitMEX, the decisive evidence was not the formal agreement — it was the promotional materials, the Discord announcements, the roadmap updates, and the internal communications that showed the issuer knew buyers were relying on managerial promises.
Murphy’s Law approaches these cases by assembling that evidentiary record first: blockchain forensic tracing to map fund flows, preservation of promotional materials and whitepaper versions, and coordination with the SEC and state regulators where parallel enforcement creates leverage. The formal contract is often the least important document in the file.
Investors who wait until enforcement is announced typically find that the issuer has already moved assets offshore, deleted social media, and retained counsel. The window for effective preservation is narrow, and it opens the moment you suspect something is wrong.
Murphy’s Law handles the legal complexity so you can focus on recovery
If you suspect you purchased a crypto asset investment contract that was never properly registered, the path forward requires legal precision, not guesswork. Murphyslawcrypto is a licensed crypto law firm with courtroom-tested experience in fraud recovery, regulatory defense, and forensic asset tracing — the exact combination this situation demands.
The firm handles the full recovery arc: preserving your evidentiary record, tracing assets on-chain, filing SEC tips and coordinating with regulators, and pursuing civil rescission or fraud claims in federal court. Clients typically retain the firm at one of three moments: when they first suspect an offering was fraudulent, when they receive an SEC inquiry, or after an enforcement action freezes platform assets. Earlier engagement consistently produces better outcomes.
To understand your legal options for crypto fraud recovery or to schedule a consultation, contact Murphy’s Law directly through the firm’s services page.
Sources
- Framework for “Investment Contract” Analysis of Digital Assets (Withdrawn) Superseded by Application of the Federal Securities Laws to Certain Types of Crypto Assets and Certain Transactions Involving Crypto Assets (Mar. 17, 2026)
- Finra
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
What is the Howey test and why does it apply to crypto?
The Howey test is the U.S. Supreme Court standard for identifying an investment contract: an investment of money in a common enterprise with an expectation of profits from others’ efforts. The SEC and federal courts apply it to crypto offerings because the test focuses on economic reality, not asset type.
Does calling a token a “utility token” exempt it from securities law?
No. The label a project assigns to its token does not control the legal analysis. If the offer and sale satisfy the Howey elements, the transaction is subject to federal securities law regardless of what the issuer calls the token.
Are SIPA and SIPC protections available for crypto held on exchanges?
Generally not. SIPA protection applies to customer property at registered broker-dealers; most crypto exchanges are not registered broker-dealers, so crypto held on those platforms is typically an unsecured claim in bankruptcy rather than protected customer property.
What is the first step if I think I bought an unregistered investment contract?
Preserve all evidence immediately: download transaction records, save promotional materials and whitepapers, and screenshot account balances. Then consult a qualified crypto attorney before taking any further action, including selling your position or communicating with the issuer.
Can I get my money back if the offering was an unregistered security?
Possibly. Section 12(a)(1) of the Securities Act of 1933 gives buyers of unregistered securities a statutory rescission right, allowing them to recover the purchase price plus interest. The viability of that claim depends on the specific facts, applicable statutes of limitations, and whether the issuer has recoverable assets.