
The SEC’s Division of Enforcement is the agency’s civil investigative and prosecutorial arm, responsible for detecting, investigating, and litigating violations of federal securities laws. When the Division prevails, it typically seeks disgorgement of ill-gotten gains, civil monetary penalties, injunctions, and industry bars that can permanently remove bad actors from the securities business. Criminal prosecution is not within the Division’s authority; when evidence supports criminal charges, the Division refers matters to the Department of Justice or U.S. Attorney offices, which handle prosecution independently.
Table of Contents
- What is the SEC Division of Enforcement and how is it organized?
- What types of violations does the Division investigate?
- How does an SEC enforcement investigation actually work?
- What remedies and penalties can the SEC obtain?
- How does the SEC Whistleblower Program work?
- Where can you find SEC enforcement records?
- What should you do if you are under SEC investigation?
- Key Takeaways
- Why most people misread an SEC investigation until it’s too late
- Murphyslawcrypto defends individuals and businesses facing SEC scrutiny
- Useful sources
- FAQ
What is the SEC Division of Enforcement and how is it organized?
The Division’s mission is to protect investors and maintain the integrity of U.S. capital markets by investigating potential violations and bringing civil enforcement actions. Former SEC Chair Gary Gensler described the Division as the “cop on the beat,” framing enforcement as the foundation of public trust in American markets. That framing captures the Division’s practical role: without credible enforcement, disclosure requirements and registration rules carry little weight.
Organizationally, the Division sits within the SEC’s broader structure and reports through its Director to the SEC Chair. Staff include attorneys, accountants, financial analysts, and industry specialists spread across the SEC’s Washington, D.C. headquarters and its regional offices nationwide. The Enforcement Manual governs internal policies and procedures, emphasizing integrity and fairness as core operating values. The Division updated the Manual in 2026 to clarify enforcement practices, improving public understanding of how cases are handled.
Specialized units allow the Division to concentrate expertise where markets are most complex:
- Crypto Assets and Cyber Unit: — targets digital asset offering fraud, unregistered crypto securities, and cyber-related misconduct
- Retail Strategy Task Force: — prioritizes cases harming retail investors, including unsuitable investment recommendations and fee abuse
| Unit | Primary Focus |
|---|---|
| Market Abuse Unit | Insider trading, market manipulation |
| Crypto Assets and Cyber Unit | Digital asset fraud, unregistered offerings, cybercrime |
| Retail Strategy Task Force | Retail investor harm, broker misconduct |
| Asset Management Unit | Investment adviser and fund fraud |
| Complex Financial Instruments Unit | Structured products, derivatives fraud |
Historically, the Division has brought a substantial number of enforcement actions annually across civil and administrative forums, relying on data analytics and these specialized teams to manage that scale.
What types of violations does the Division investigate?
The Division’s caseload spans a wide range of securities law misconduct. Case selection shifts with market conditions, which is why digital assets have drawn increasing attention alongside traditional fraud categories.
- Accounting and financial statement fraud: — Companies falsifying revenue figures or concealing liabilities to mislead investors, as seen in large-scale restatement cases
- Market manipulation: — Coordinated “pump and dump” schemes that artificially inflate a stock’s price before insiders sell at the peak
- Offering and IPO fraud: Unregistered securities offerings, false prospectuses, and, increasingly, fraudulent initial coin offerings (ICOs) and token sales; the Division’s crypto-specific enforcement posture has expanded substantially in recent years
- Investment adviser and broker-dealer misconduct: — Undisclosed conflicts of interest, churning client accounts, and misappropriation of client funds
Each category carries its own evidentiary demands. Insider trading cases often hinge on communications records and trading data; accounting fraud requires forensic accounting analysis; crypto fraud cases add blockchain forensics and jurisdictional complexity that traditional enforcement tools were not designed to handle.
How does an SEC enforcement investigation actually work?
Understanding the Division’s process matters whether you are a potential complainant, a witness, or a subject. The sequence below reflects the typical lifecycle, though complex cases can compress or extend any phase.
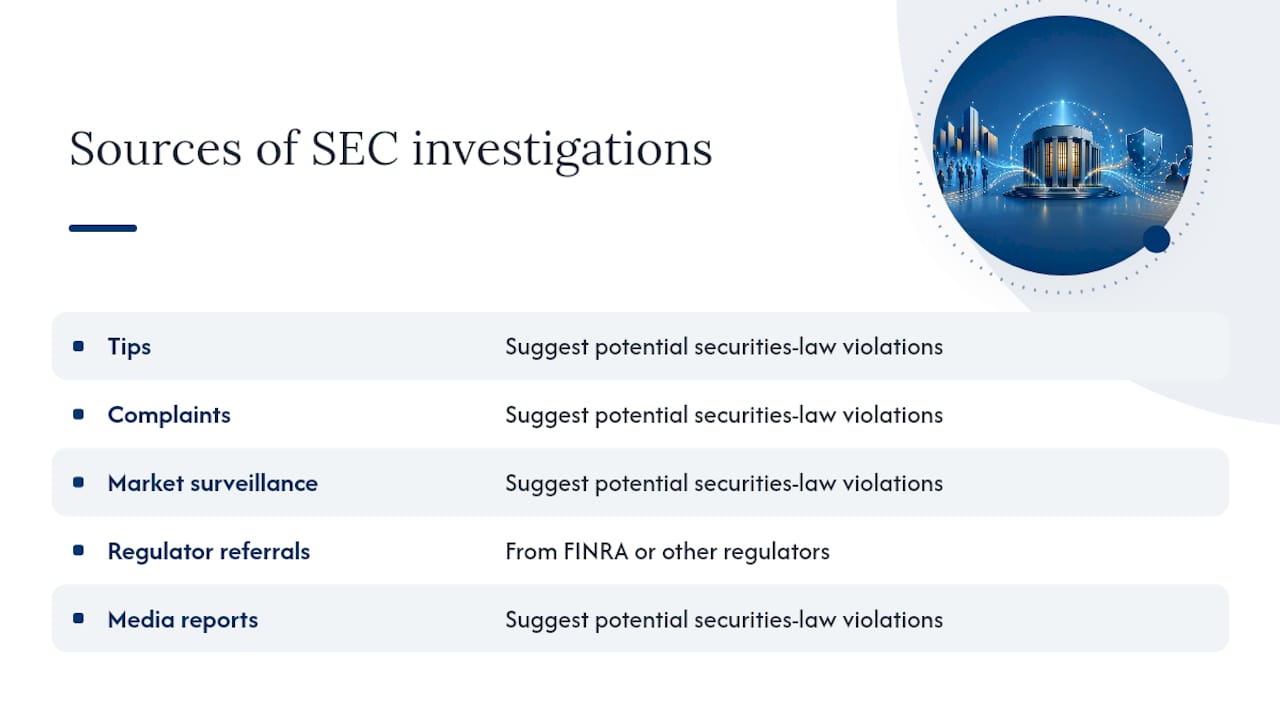
- Intake: — The Division receives tips, complaints, referrals from other SEC offices, self-regulatory organizations like FINRA, and media reports. Market surveillance systems also flag anomalous trading patterns automatically.
- Resolution: — Most matters settle through consent decrees or settlement orders. Contested cases proceed to trial before a federal judge or an Administrative Law Judge (ALJ).
Administrative proceedings vs. federal civil court is a distinction that carries real consequences. Administrative proceedings use an ALJ within the SEC, with a separate internal appeals path to the Commission and then to a federal circuit court. Federal civil suits proceed in U.S. district court under the Federal Rules of Civil Procedure, with broader discovery rights and a jury trial option in some circumstances. Respondents in administrative cases face different discovery mechanics and a faster timeline than defendants in federal court.
All SEC investigations are conducted privately until the Commission authorizes filing. Many subjects mistakenly assume an inquiry is public, a misunderstanding that can cause serious reputational damage if handled without counsel.
Key procedural fact: The Division cannot issue compulsory subpoenas until a formal order of investigation is issued. Before that order, all cooperation is voluntary.
What remedies and penalties can the SEC obtain?
The remedies the Division pursues are civil in nature, not criminal. They include:
- Disgorgement: — Repayment of profits gained through the violation. When disgorgement is ordered, funds are often returned to harmed investors through distribution programs.
- Injunctions: — Court orders prohibiting future violations of specific securities laws, enforceable through contempt proceedings.
- Cease-and-desist orders: — Available in administrative proceedings, these direct a respondent to stop ongoing violations without requiring a court order.
- Trading suspensions: — The SEC can suspend trading in a security for up to ten days when it believes investors lack accurate information.
In practice, settlements typically combine multiple remedies. A typical resolution might include disgorgement of gains, a civil penalty, and a five-year industry bar, with the disgorgement amount returned to investors through a Fair Fund. The collateral consequences extend beyond the formal order: executives face loss of professional licenses, D&O insurance complications, and reputational damage that affects future employment. For Securities Exchange Act violations, the statutory penalty tiers are set by Congress and adjusted periodically for inflation.
How does the SEC Whistleblower Program work?
Tips from the public are not peripheral to the Division’s work; they are often central to detecting complex schemes that evade routine market surveillance. The SEC’s whistleblower program formalizes that relationship and creates financial incentives for reporting.
Submitting a tip follows a defined process:
- Go to the SEC’s investor education resources at Investor.gov or the SEC’s Tips, Complaints, and Referrals (TCR) portal to access the submission form.
- Complete the TCR form with as much specific detail as possible: names, dates, transaction details, and supporting documents.
- Submit electronically through the SEC’s online portal. You may submit anonymously if represented by an attorney.
- The Division reviews submissions and may follow up for additional information.
Award eligibility requires that the information be original, that it lead to a successful enforcement action resulting in monetary sanctions exceeding $1 million, and that the whistleblower not have obtained the information through illegal means. Awards range from 10% to 30% of the sanctions collected.
Pro Tip: Before submitting a whistleblower complaint, consult with counsel who handles SEC matters. An attorney can help you structure your submission for maximum impact, protect your identity if you choose anonymous filing, and advise you on any potential exposure you may have. The SEC whistleblower defense guide at Murphyslawcrypto covers the defense-side considerations in detail.
Where can you find SEC enforcement records?
Primary sources for enforcement records are all publicly available. The table below maps each record type to its location.
| Record Type | Where to Find It |
|---|---|
| Litigation releases | SEC.gov Litigation Releases index |
| Administrative proceedings | SEC.gov Administrative Proceedings index |
| ALJ decisions and appeals | SEC.gov ALJ Decisions page |
| EDGAR filings (8-K, 10-K, etc.) | EDGAR full-text search at efts.sec.gov |
| Enforcement press releases | SEC.gov Newsroom |
| Whistleblower program resources | SEC Office of the Whistleblower page |
Practical search tips:
- Use the SEC’s Litigation Releases page and filter by date or respondent name to locate civil injunctive actions filed in federal court.
- EDGAR’s full-text search accepts company names, CIK numbers, and docket references; an 8-K filed under Item 8.01 often discloses an SEC investigation or settlement.
- Administrative proceeding orders are indexed by respondent name and release number on the SEC’s Administrative Proceedings page.
- ALJ initial decisions and Commission opinions on appeal are published separately; check both when researching a contested administrative case.
What should you do if you are under SEC investigation?
Receiving a subpoena, a Wells Notice, or even an informal inquiry letter from the Division requires an immediate, structured response. The following steps reflect counsel-level practice.
- Preserve all documents immediately — Issue a litigation hold to all relevant custodians. Destruction of documents after receiving notice of an investigation can result in obstruction charges separate from the underlying securities matter.
- Retain experienced securities counsel — Choose counsel with actual SEC enforcement experience, not just general litigation background. The Division’s staff are specialists; your representation should match that level.
Pro Tip: A Wells Notice is the Division’s formal signal that staff intend to recommend charges. You have the right to submit a Wells Submission responding to the proposed charges before the Commission votes. A well-crafted Wells Submission, prepared by experienced counsel, has resolved matters without formal charges in numerous cases.
When DOJ involvement is present or likely, the strategy changes materially. Civil cooperation with the SEC can create a record that federal prosecutors use. Counsel experienced in civil vs. criminal crypto fraud distinctions is particularly important when digital asset conduct is at issue, given the overlapping jurisdictional claims between the SEC, CFTC, and DOJ.
Key Takeaways
The SEC Division of Enforcement is the agency’s civil arm, and understanding its process, remedies, and your rights is the single most important step before responding to any inquiry.
| Point | Details |
|---|---|
| Division’s core role | The SEC Division of Enforcement investigates and litigates civil securities law violations; criminal charges go to DOJ. |
| Investigations are private | The SEC does not publicly disclose an investigation until it files; assuming otherwise can cause unnecessary reputational harm. |
| Subpoenas require a formal order | Compulsory document and testimony demands only become available after the Commission issues a formal order of investigation. |
| Remedies stack | Disgorgement, civil penalties, injunctions, and industry bars are routinely combined in a single settlement. |
| Murphyslawcrypto | Murphyslawcrypto provides enforcement defense, crypto fraud recovery litigation, and compliance consulting for individuals and businesses facing SEC scrutiny. |
Why most people misread an SEC investigation until it’s too late
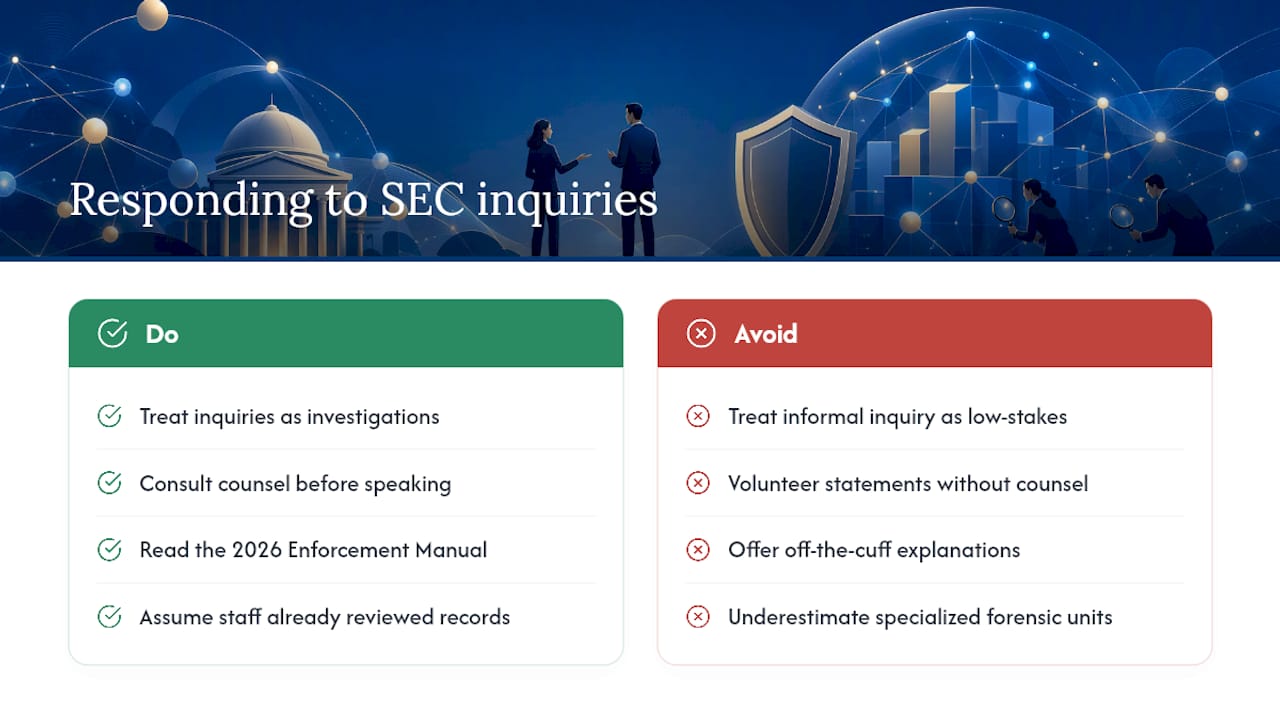
The most consistent mistake respondents make is treating an informal SEC inquiry as a low-stakes administrative formality. It is not. By the time Division staff send an informal document request, they have typically already reviewed trading records, communications, and third-party data. The investigation is not beginning; it is already underway.
A second, related error is the instinct to explain. Executives who believe they have done nothing wrong often want to tell their story directly to SEC staff, without counsel, on the theory that transparency will close the matter quickly. That instinct is understandable and almost always counterproductive. Voluntary statements made in informal interviews are not protected, and a single poorly worded answer can reframe an entire investigation.
The 2026 updates to the Enforcement Manual signal that the Division is investing in clearer public communication about how it operates. That transparency is genuinely useful for practitioners and respondents who take the time to read it. But clarity about process does not reduce the stakes of a misstep. The Division’s specialized units, particularly the Crypto Assets and Cyber Unit, bring forensic depth that general corporate counsel rarely matches. Liam Murphy’s work on matters involving Celsius, Terraform Labs, and BitMEX reflects exactly the kind of enforcement-adjacent litigation experience that shapes realistic expectations about what the Division can and will do when it has a strong case.
Murphyslawcrypto defends individuals and businesses facing SEC scrutiny
If you or your company has received an SEC subpoena, a Wells Notice, or an informal inquiry, the time to act is before your first response, not after.
Murphyslawcrypto, founded by Liam Murphy, Esq. (Penn Law, formerly Paul Hastings, Selendy Gay, and McKool Smith), provides enforcement defense, crypto fraud recovery litigation, and compliance consulting for individuals and businesses facing SEC and DOJ scrutiny. The firm has litigated significant matters involving Celsius, Terraform Labs, and BitMEX, and maintains an active docket of fraud recovery and regulatory defense cases. Unlike general litigation firms, Murphyslawcrypto combines courtroom experience with blockchain forensics and a deep understanding of how the Division builds its cases. If you need to respond to a regulatory inquiry, contact the firm for a consultation and bring any documents you have received so counsel can assess your position from the first conversation.
Useful sources
These primary sources provide authoritative detail on the Division’s structure, procedures, and enforcement records:
- About the Division of Enforcement
- Enforcement and litigation
- Office Hours with Gary Gensler (Division edition) — What does the SEC Division of Enforcement do?
- How investigations work
- SEC’s Division of Enforcement announces updates to Enforcement Manual
- SEC Division of Enforcement: What It Is, How It Works
Consult the Enforcement Manual and the How Investigations Work page for procedural detail; use the Litigation Releases and Administrative Proceedings indexes to research specific cases; and use Investor.gov for whistleblower program guidance.
This article provides general legal information, not legal advice. Rules, procedures, and penalty amounts change; confirm current requirements with the SEC’s official publications or a qualified securities attorney.
FAQ
What does the SEC enforcement division do?
The SEC Division of Enforcement investigates potential violations of federal securities laws and brings civil actions in federal court or through administrative proceedings. It seeks remedies including disgorgement, civil monetary penalties, injunctions, and industry bars.
What is a SEC enforcement action?
An SEC enforcement action is a formal civil proceeding the Commission initiates after its Division of Enforcement recommends charges. Actions are filed either in federal district court or as administrative proceedings before an Administrative Law Judge.
Why would the SEC investigate someone?
The Division opens investigations based on tips, complaints, market surveillance data, referrals from FINRA or other regulators, and media reports suggesting potential securities law violations such as insider trading, fraud, or unregistered offerings.
What is the difference between SEC enforcement and criminal prosecution?
The SEC brings civil enforcement actions and cannot file criminal charges. When evidence supports criminal prosecution, the Division refers the matter to the Department of Justice or a U.S. Attorney’s office, which handles criminal proceedings independently.
Can Murphyslawcrypto help if I receive an SEC subpoena?
Yes. Murphyslawcrypto provides enforcement defense for individuals and businesses facing SEC investigations, including subpoena response, Wells Submission preparation, and coordination with DOJ when criminal exposure is present.